NetSuite Equipment Rental Billing and Asset Requirements
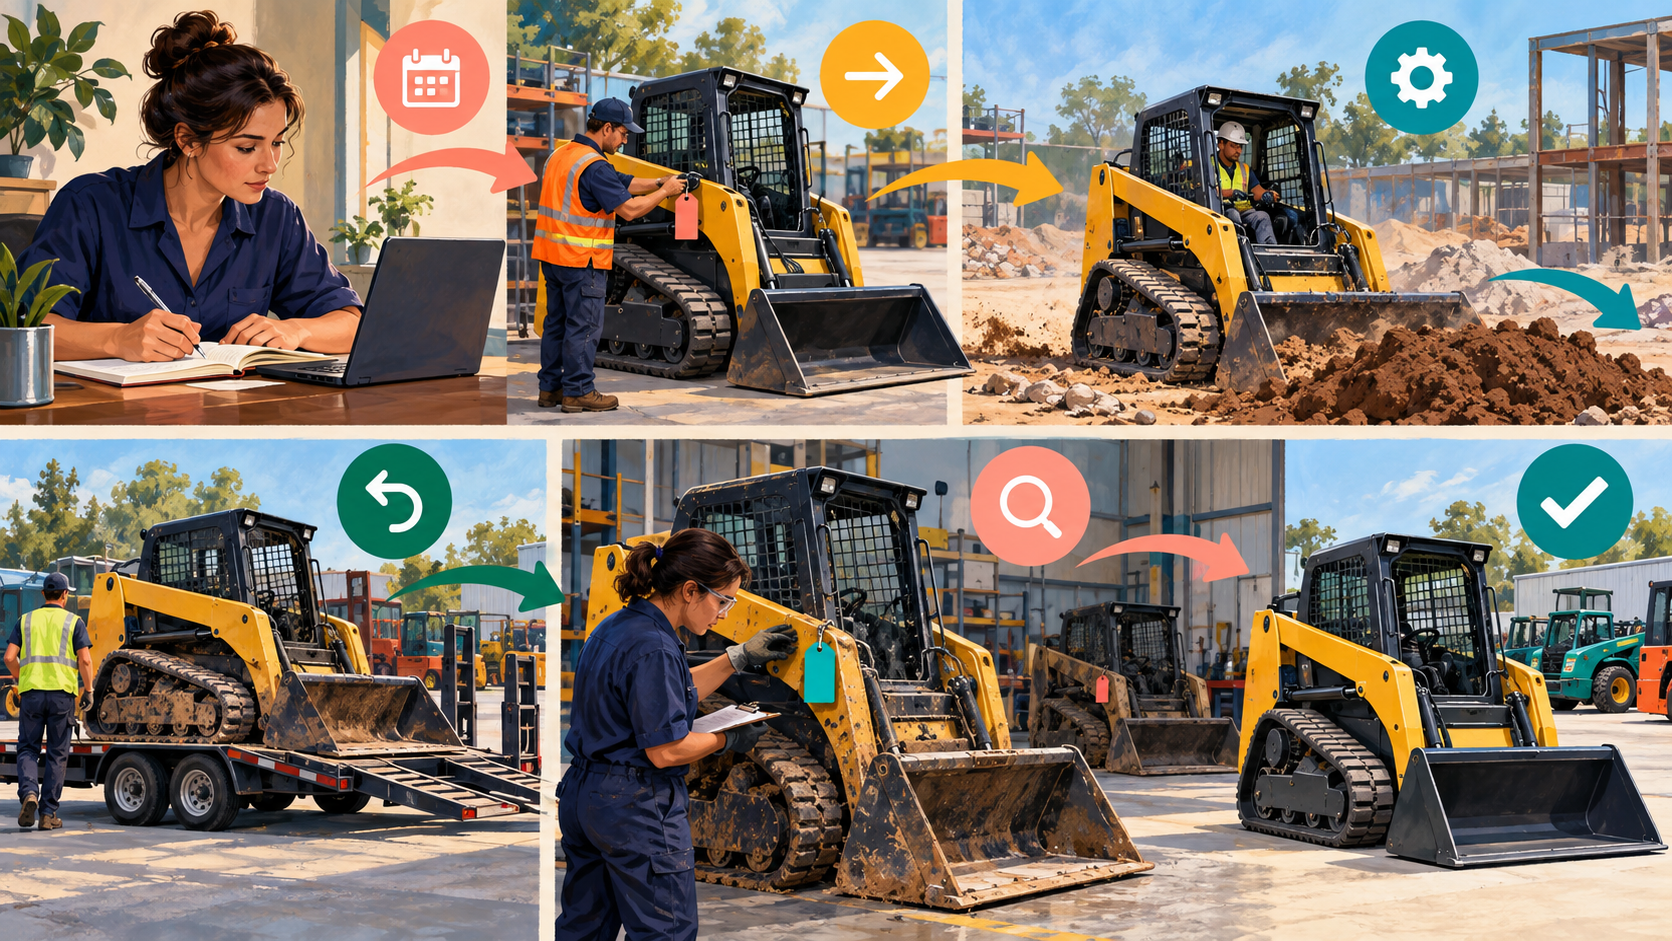
Equipment rental design in NetSuite needs to connect asset availability, rental periods, customer charges, return inspection and asset accounting. Start with the physical rental lifecycle. Depreciation records and recurring invoices do not by themselves establish whether a particular machine is available, on hire, awaiting collection or unsafe to rent again.
Define the operating states and their financial consequences before evaluating a rental SuiteApp or integration. This makes demonstrations more useful and prevents a billing workaround from becoming the only record of where equipment actually is.
Identify the equipment at the right level
Decide which assets require individual serial tracking and which can be managed as a quantity pool. A high-value machine with maintenance history usually needs a different record model from interchangeable low-value accessories.
Record ownership, home location, current location, condition and relevant operating specifications. Distinguish company-owned rental assets from customer-owned equipment and supplier-provided equipment. The same physical description does not imply the same accounting treatment.
Define the relationships among item records, rental equipment records and fixed-asset records. Give each a clear purpose and a stable cross-reference. An operator should not need to infer the accounting asset from a free-text nickname on the rental contract.
Design an availability state model
List reservation, available, dispatched, on rent, off rent, in transit, awaiting inspection and maintenance states as applicable. For each transition, specify the evidence and authorized role. A return receipt does not necessarily make equipment available for another customer.
Decide how future reservations interact with maintenance and expected returns. Test overlapping bookings and late returns. A calendar showing an asset as free should be supported by the actual operating state and the approved planning rules.
Separate the physical location from commercial responsibility. Equipment can remain at a customer site after the customer has requested off-rent collection. The contract determines whether billing continues, while operations still needs to arrange recovery.
Specify the rate calculation precisely
Record daily, weekly or monthly rates, minimum terms, included usage and additional charges. Define how partial periods are handled and whether a longer period replaces accumulated daily charges or adds another tier.
State the time zone and timestamp that start and stop billing. Include delivery, collection, standby, breakdown and replacement scenarios. A dispute often arises from these boundaries rather than from the headline rate.
Treat equipment usage and rental duration as separate quantities when the contract includes both. A machine may have an agreed weekly rental fee plus excess operating-hour charges. Preserve the meter readings and the approved calculation rather than deriving everything from elapsed calendar time.
Distinguish rental operations from asset accounting
Fixed Assets Management supports asset-related accounting processes such as depreciation, transfers, disposal and revaluation. Those functions need to connect to rental activity without being mistaken for a complete rental scheduling or pricing engine.
The documented FAM lease-record process concerns assets leased from a lessor. It should not be assumed to provide the complete customer rental workflow for equipment your business rents out. Confirm the required capabilities in the selected solution.
Ask the accounting owner to define capitalization, depreciation, repair expense and disposal treatment. The operational decision that a unit is off rent does not automatically determine its accounting status or useful life.
A hypothetical rental contract
Assume a fictional rental agreement charges USD 250 per day for three billable days, plus USD 100 delivery and an approved USD 150 damage charge. Tax is excluded. The expected invoice is USD 1,000: 750 plus 100 plus 150.
The customer has paid a USD 400 deposit. If the approved process applies that deposit to the invoice, USD 600 remains to collect. The deposit application should be visible separately from the USD 1,000 charge calculation.
Now suppose the customer requests off-rent at 16:00 on the third day, but collection occurs the next morning. The billing outcome depends on the agreement's cutoff and collection rules. Preserve both events. Changing the return timestamp to make the amount look correct would weaken the operational history.
After collection, inspection identifies damage. The unit remains unavailable until the authorized repair and release steps are complete. That availability decision is separate from whether the customer has paid the damage invoice. These figures and events are hypothetical acceptance-test inputs.
Control deposits, damage and credits
Record what a deposit secures and when it can be applied or refunded. Confirm currency, contract reference and the approved customer-balance process. An operational deposit field without an accounting reconciliation can become a source of disputes.
Require evidence and approval for damage charges. Preserve condition at dispatch and return, the assessment and the customer's applicable terms. Do not treat every repair cost as automatically recoverable from the last renter.
Test credits for breakdowns, replacements and early returns. A credit may affect the invoice while the equipment remains physically with the customer. Keep commercial status and asset status independently accurate.
Evaluate the selected rental solution end to end
Ask a vendor to demonstrate the same equipment through reservation, dispatch, extension, partial return, inspection and final billing. Include an overlapping booking and an offline or delayed field update if relevant.
Confirm which records the extension creates and which NetSuite processes it uses. Review supported subsidiaries, currencies, roles and integration routes. Feature availability and country support can vary by SuiteApp and implementation.
Test whether a retry duplicates an invoice or changes the rental stop date. Reconcile the rental contract's charge schedule to issued invoices, credits, deposits and the final customer balance. A visually complete rental screen is not sufficient evidence of correct accounting.
Build useful fleet measures
Define utilization with a clear denominator. Calendar days, available-for-rent days and billable days produce different ratios. Show downtime and maintenance separately so the business can distinguish demand problems from unavailable equipment.
Measure revenue and direct service costs by equipment or equipment class where the data supports it. Keep depreciation and allocated overhead identifiable. Comparing units with different age, capacity or maintenance cycles requires context.
A CuriousRubik NetSuite implementation review can use one difficult rental contract to define these requirements. The result should be a tested connection between the physical asset, the customer agreement and the financial records.
Frequently asked questions
Does Fixed Assets Management provide complete rental billing?
Do not assume it does. Asset accounting and customer rental operations are different requirements. Demonstrate scheduling, on-rent and off-rent states, rates, deposits and returns in the selected rental design.
When should rental billing stop?
Use the contract's approved rule and preserve the supporting event. Off-rent request, physical collection and inspection can occur at different times, so record them separately rather than forcing one timestamp to serve every purpose.
Should returned equipment immediately become available?
Only after the required inspection and release steps. Physical receipt, financial settlement and readiness for the next rental are distinct states with different owners and evidence.
Are customer damage charges equal to repair costs?
Not automatically. Recovery depends on the agreement, evidence and approved assessment. The repair expense and customer charge should remain separately traceable even when their amounts happen to match.
Which utilization percentage should management use?
Define the decision first and state the denominator. Billable days divided by calendar days differs from utilization of available fleet time. Present downtime separately so the ratio remains interpretable.
Related reading