NetSuite Return Inspection and Resalable Stock Decisions
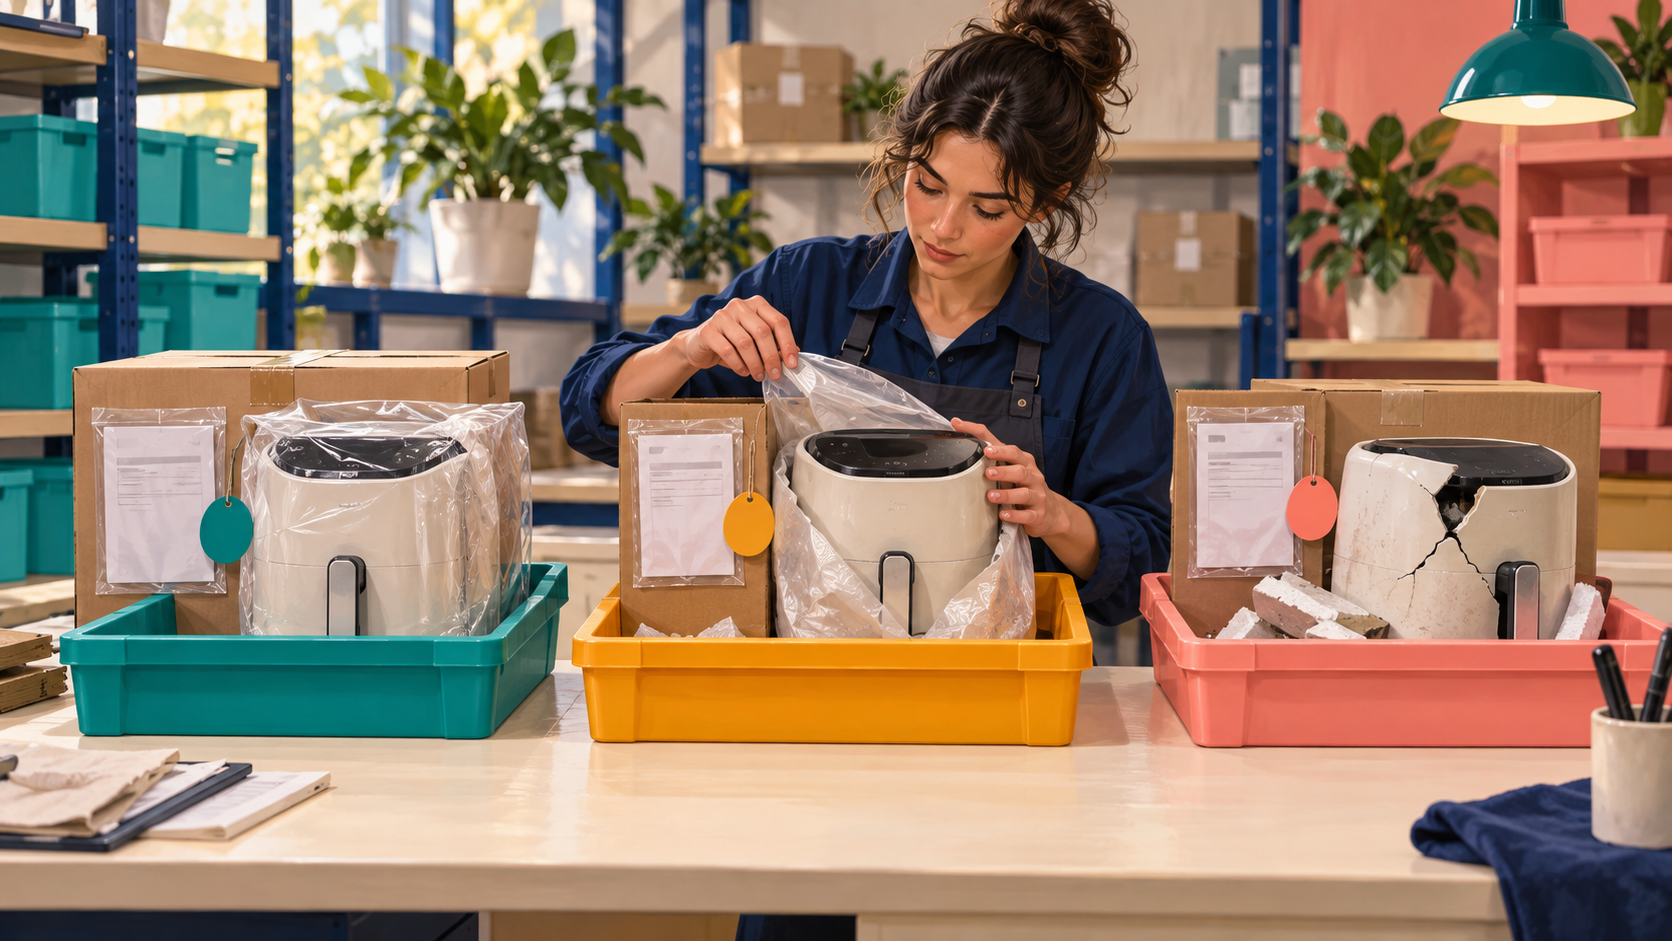
Receive a customer return according to its actual quantity and identity, then make a separate, evidenced decision about whether it may become saleable stock. The return authorization, receipt, inspection result, inventory status, and customer refund represent different decisions. Their sequence should be explicit before automation is added.
The critical control is the interval between physical arrival and release for resale. A returned unit should not become available to the next customer simply because a receiver completed a familiar form.
Define the arrival and disposition states
Start with a small set of operational outcomes: awaiting inspection, approved for resale, approved for repair or other controlled processing, and approved for write-off or disposal. Specify the evidence and authorized role for each transition.
Capture item, quantity, unit, original shipment relationship where available, lot or serial identity, return reason, physical condition, receiving location, and inspection owner. Customer-reported condition is useful context but should not replace the actual inspection.
Keep financial decisions separate. The customer may be entitled to a refund even when goods are damaged, or a commercial dispute may remain after goods are physically accepted. The responsible customer-service and finance owners should decide the credit or refund under the approved policy.
Understand what Restock means
With Advanced Receiving, returned inventory can be restocked or written off through the receipt's Restock choice. Restocking increases inventory quantity and value; clearing the choice follows a write-off treatment rather than adding the goods back to inventory.
That distinction makes “leave Restock unchecked until inspection” an unsafe universal instruction. It can create a financial disposition when the business merely intended to hold goods temporarily. Design the inspection workflow with the accountant and warehouse owner before selecting defaults.
When the approved process records returned goods in inventory while withholding them from sale, verify the appropriate inventory status and physical hold. Inventory recognition and saleable availability are separate concerns. A status change itself does not replace a required financial transaction.
Design the inspection holding process
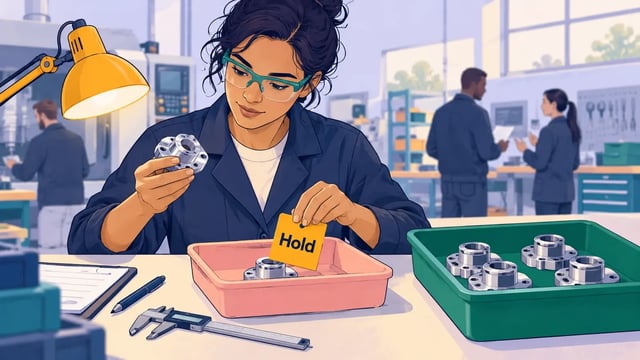
Choose a clearly identifiable return area or bin arrangement. Staff should be able to distinguish uninspected returns from saleable stock and from supplier returns or ordinary damaged inventory. Labels should include the return reference and relevant item identity.
Define who can release stock. Technical permission to enter a status change may not enforce every desired approval boundary. Confirm whether the control is native, workflow-based, scripted, or manual, and test the actual entry routes.
If quality or repair SuiteApps are used, identify their supported records and dependencies. A general inventory status does not automatically create an inspection, repair case, or refund approval. Avoid using one label to imply an entire lifecycle.
Hypothetical mixed-condition return
A customer returns 20 devices against one authorization. Inspection finds 12 fit for resale, five requiring repair evaluation, and three beyond economic repair. The warehouse records the actual identities and quantities received, then applies the approved disposition process.
Only the 12 released devices become saleable. The five awaiting repair remain physically and systematically held. Finance reviews the treatment of the three rejected devices and the appropriate transaction for their disposition. The customer credit decision follows the agreed return policy and evidence.
A blanket status change on all 20 would incorrectly release eight units. A blanket write-off could remove value and quantity the business intended to recover. The process must support the distinct outcomes without losing their connection to the original return.
If the selected mobile flow cannot apply different restock choices to partial quantities on the same line, test a supported processing design rather than assuming the screen can split them. Keep the resulting receipts and disposition records reconcilable to the 20 physical units.
Test mobile receiving preferences
NetSuite WMS return receiving can expose a Restock choice depending on activated rules. The mobile process has specific constraints: one restock setting applies to partially received items, and manual item-receipt posting affects whether the operator can change that field in the app.
Document the actual preference and default in the account. A warehouse team following a screenshot from another configuration may produce a different result. Test the role, transaction type, partial receipt, and posting route used in production.
After mobile processing, inspect the posted item receipt and inventory detail. Confirm the intended status, bin, quantity, and Restock result. A mobile completion message is not a substitute for checking the financial and quantity outcome.
Verify identity before releasing a return
For serialized items, compare the returned serial with the authorized product and original shipment evidence where available. For lots, preserve the returned lot and evaluate expiry or customer-specific shelf-life constraints before resale.
A returned carton can contain the wrong product, mixed lots, missing accessories, or altered packaging. Define how these exceptions are held and investigated. Do not assign a convenient lot or serial just to satisfy required inventory detail.
Where kits or bundles are involved, route the composition decision to the established item and return design. This inspection process should not invent a new kit mapping. The warehouse needs a clear expected physical contents list and an approved route for incomplete returns.
Sequence refund and stock release independently
Write two linked decision paths. One determines whether the customer's financial remedy is approved. The other determines whether the returned goods can be sold, repaired, returned to a vendor, or disposed of. They may reach conclusions at different times.
If refunds can occur before physical return under an approved policy, preserve that fact in the inspection queue. Refunding the customer does not prove that the goods arrived. If goods arrive before a dispute is settled, receiving should not automatically imply that a refund has been approved.
For ecommerce or payment integrations, verify how the approved credit or refund event reaches the external system through its separate integration test plan. Avoid using an inventory-status change as an undocumented trigger for money movement.
Control reversals and reinspection
A release decision may need reversal when a later defect is discovered. Test how the affected quantity is identified and held again, including stock already allocated or picked. Escalate any shipped quantity through the organization's quality process.
For a receipt entered incorrectly, use the supported correction route and examine related credits, refunds, inventory detail, and downstream movements. An unrelated adjustment can make the stock total look right while leaving the return history inconsistent.
Keep inspection evidence and approval with the quantity affected. Record the previous and new disposition, responsible person, and reason. This helps distinguish a corrected data-entry error from a genuine change in product condition.
Accept the workflow with a resale attempt
A meaningful test attempts to allocate or pick an uninspected return through each relevant route, then repeats the action after an authorized release. Verify both the intended hold and the ability to sell correctly released goods.
Also test partial release, wrong serial, expired lot, missing item, mobile posting failure, and a customer refund completed before receipt. Reconcile received quantity to released, held, and financially disposed quantities, without double counting.
CuriousRubik's NetSuite support services can support review of that sequence and its account-specific controls. The goal is a defensible resalable-stock decision with clear financial ownership.
Frequently asked questions
Does Restock mean the returned item is automatically fit for resale?
It records inventory treatment, not an inspection conclusion. The business should separately verify condition and configure any required hold status and physical segregation before releasing returned stock to customers.
Can we leave Restock unchecked while waiting for inspection?
Do not use that as a universal holding method. Clearing Restock follows write-off treatment rather than adding the item back to inventory. Agree the intended receipt and inspection accounting with finance first.
Can one return contain saleable and rejected quantities?
Yes operationally, but the transaction design must preserve each disposition. Test the supported receipt and mobile behavior, especially partial-line restock restrictions, rather than assuming every form can split the quantities as desired.
Does issuing a refund release returned stock?
It should not be assumed to. Customer financial remedy and inventory resale eligibility are separate decisions. Link their evidence while keeping the approved refund and inspection processes distinct.
What proves that an inspection hold works?
Test an attempted allocation or pick before release, the authorized release action, and the resulting allowed sale. Confirm physical segregation and all relevant transaction routes, not merely the presence of a status name.
Related reading