Keep the current explanation connected to its evidence.
When a late ledger adjustment changes a previously shared AI finance answer, correct the answer's distribution as well as its calculation. Regenerating a paragraph leaves the old explanation in meeting packs, messages and downloaded files. The team needs to know which version is current and whether an earlier decision depended on the retired one.
This is especially relevant to a Singapore regional finance team that distributes commentary before every contributing entity has finished its review. The underlying report can change after the narrative has travelled. A useful correction process links each answer to a defined evidence version, identifies affected readers and preserves the reason for replacement.
The process below is a proposed operating control. It does not assume that NetSuite or an AI product automatically finds every copy of an answer or withdraws it from circulation.
Follow one answer through a late adjustment
The following example is entirely illustrative. All figures are synthetic SGD management-reporting amounts, already presented on one agreed entity, period and currency basis. They are not product performance data or accounting advice.
At 09:00 on 8 October, a Singapore finance analyst prepares evidence pack E17 for a regional management discussion. It shows current-period operating expenses of SGD 108,000 against SGD 100,000 in the comparison period. The approved comparison is therefore an increase of SGD 8,000, or 8%.
A proposed AI assistant drafts answer A17: “Operating expenses are 8% above the comparison period. The increase reflects additional activity across the region.” A reviewer confirms the arithmetic but overlooks that the pack does not establish the cause. The answer is distributed in a meeting pack and a finance-team message.
At 14:00, an authorised finance reviewer approves a late adjustment of SGD 12,000 into the same current-period scope. The revised expense amount is SGD 120,000. The movement is now SGD 20,000, or 20%. The original answer contains both a stale figure and an unsupported explanation.
The correction must address both. Replacing “8%” with “20%” would preserve the invented cause and obscure why the narrative changed.
Establish what the evidence actually proves
Prepare evidence pack E18 with the revised report, the adjustment reference and a reconciliation from E17. Confirm that entity scope, accounting book where relevant, period basis, currency presentation and comparison population remain unchanged. Otherwise the adjustment alone cannot explain the full difference.
In this example, the bridge is straightforward: SGD 108,000 plus the approved SGD 12,000 adjustment equals SGD 120,000. The comparison remains SGD 100,000. The source pack supports the change in reported expenses; it does not establish that regional activity caused it.
A corrected answer A18 could read: “Operating expenses are SGD 120,000, 20% above the comparison period's SGD 100,000. This replaces the earlier 8% comparison following a SGD 12,000 adjustment included in evidence pack E18. The available evidence does not establish the operational cause of the remaining movement.”
Finance must decide what causal explanation, if any, can be added after investigation. The AI should receive only the approved evidence needed to draft that explanation, with uncertainty preserved.
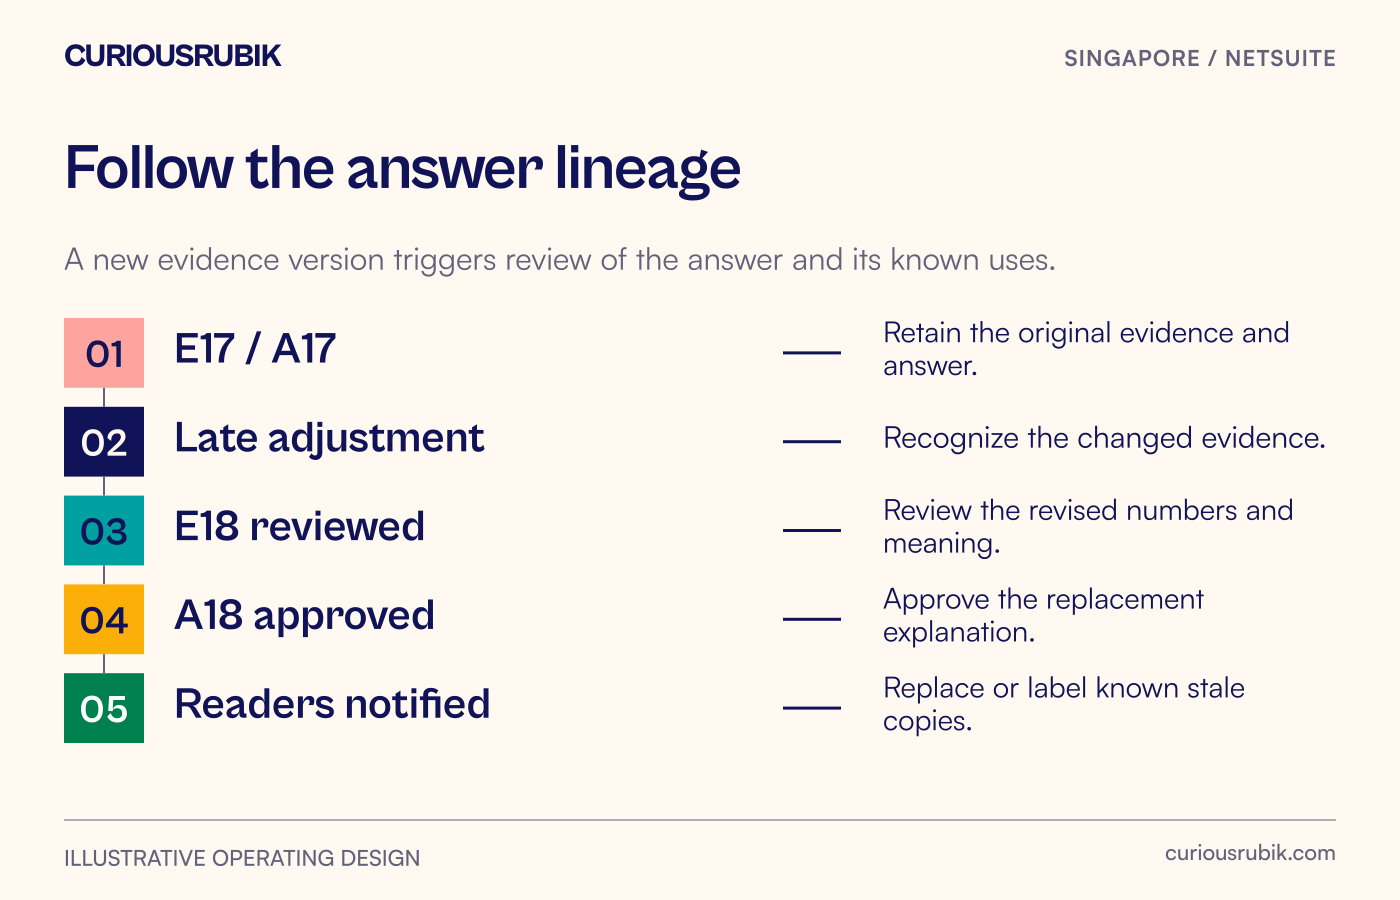
Keep a supersession record that a colleague can follow
Use one record for the answer lineage. In the illustrative case, fill it as follows:
- Answer identity: A17, issued 8 October at 09:30, based on E17 extracted at 09:00. Record the actual report definition and scope alongside the extract time.
- Change event: the authorised adjustment added SGD 12,000 to the defined expense population at 14:00. Link its evidence in the controlled finance workspace.
- Replacement: A18, based on E18, approved by the designated finance reviewer. A17 is marked superseded with a pointer to A18; its original text remains available to authorised reviewers.
- Known distribution: management meeting pack version 1 and the finance-team message. Name the person responsible for replacing the pack and posting the correction in the original message context.
- Decision exposure: the controller checks whether any cost action or forecast update relied on A17. Record the result and any further review required.
Use actual timestamps and acknowledgements in the live record. The example's dates illustrate a sequence, not a recommended close timetable or mandatory retention period.
Preserving the retired answer helps explain what readers saw. Keeping it unlabelled beside the replacement creates two competing answers. Control both accessibility and status so authorised reviewers can reconstruct events without encouraging routine use of the obsolete version.
Send a correction that says what changed
The following is an illustrative internal notification draft, not a sent message:
“Please use answer A18 and meeting pack version 2 for the operating-expense comparison. The current-period amount is now SGD 120,000 and the comparison is 20%, following a SGD 12,000 adjustment. A17's 8% figure is superseded. Its explanation about regional activity was not supported by the evidence and has been removed. If you used A17 in another document or a decision, please tell the controller so that copy or decision can be reviewed.”
Adapt the recipient list to the actual distribution and confidentiality boundary. A correction about an aggregate management figure does not automatically authorise sending the underlying journal, account detail or sensitive supporting documents to every reader.
If the answer reached an external audience, the responsible finance and communications owners should approve the specific corrective message and destination. The internal example does not settle external disclosure obligations.
Separate the product capability from the correction process
NetSuite OneWorld supports consolidated reporting across subsidiaries, but report support and selected subsidiary context matter. Oracle documents different currency presentation for individual-subsidiary and consolidated reporting. Record those choices in the evidence definition so an answer does not silently switch basis when regenerated.
Oracle also documents administrative control over available AI agents and their role access. That is a capability boundary, not evidence that this answer-supersession workflow exists in a particular account. Verify the proposed AI route, permissions and data handling. A custom workflow needs an owner for its version register, distribution tracking and review controls.
Do not give a drafting assistant authority to post the adjustment, approve the accounting treatment or decide who should receive sensitive finance information. Those are separate controlled actions. The correction process starts from a change approved through the company's actual finance procedure.
Rehearse the mistakes that make old answers persist
Test the process with three deliberately seeded failures before relying on it:
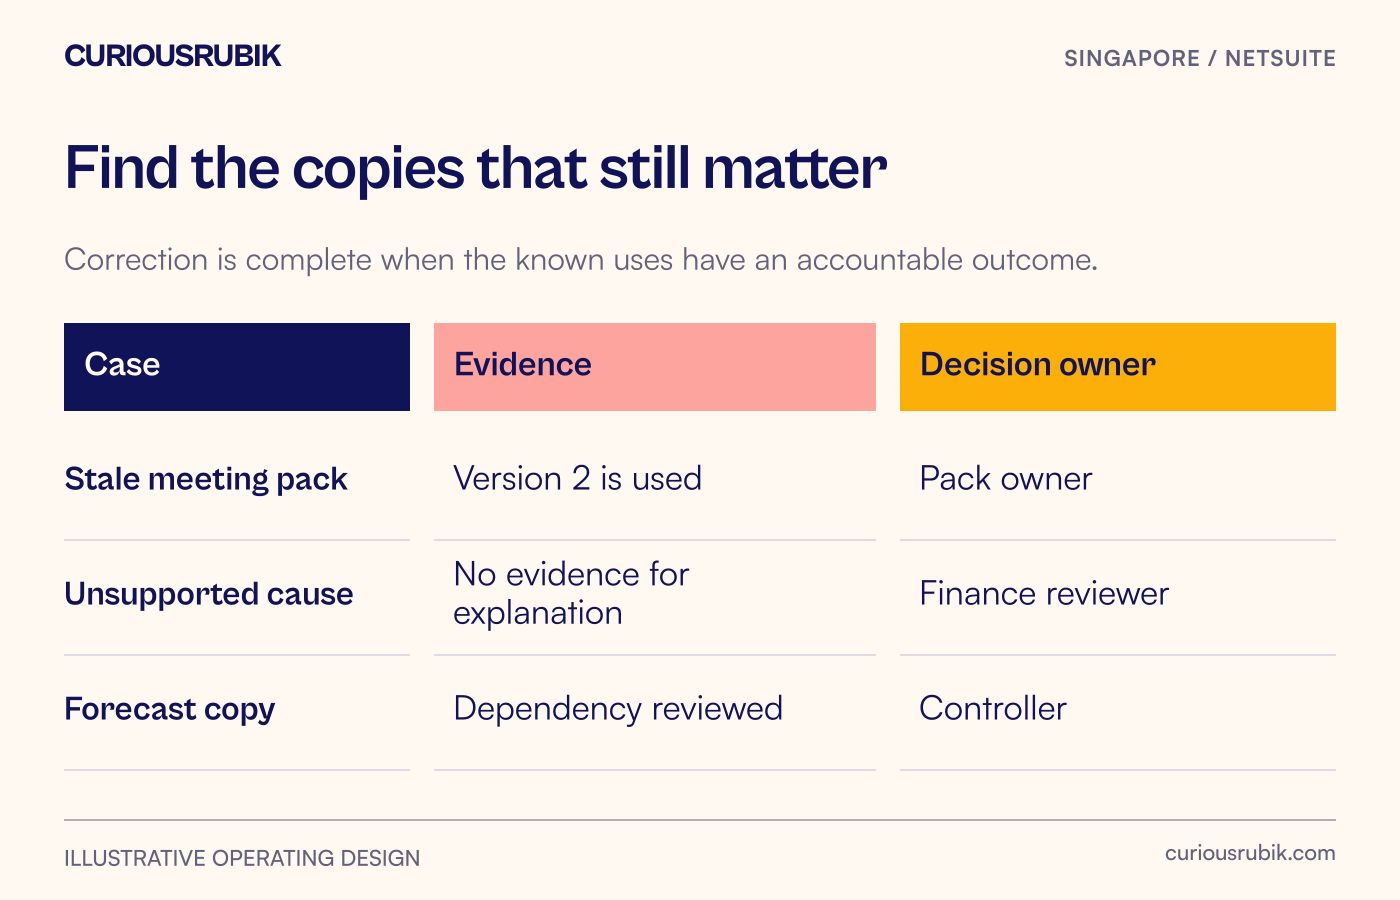
- A stale attachment remains in the meeting folder. The pack owner must label or replace the accessible version and verify which version the meeting uses.
- The regenerated answer uses E18 but keeps A17's unsupported causal sentence. The finance reviewer must reject it even though the percentage is correct.
- A reader copied A17 into a forecast note. The controller must review that dependency rather than close the correction when the original message is edited.
The AI accuracy and human-approval guide helps assess an answer before release. This later control protects the team when valid evidence changes or a missed error emerges. Start with one recurring management explanation, map where it travels, and give its owner a practical way to retire it.