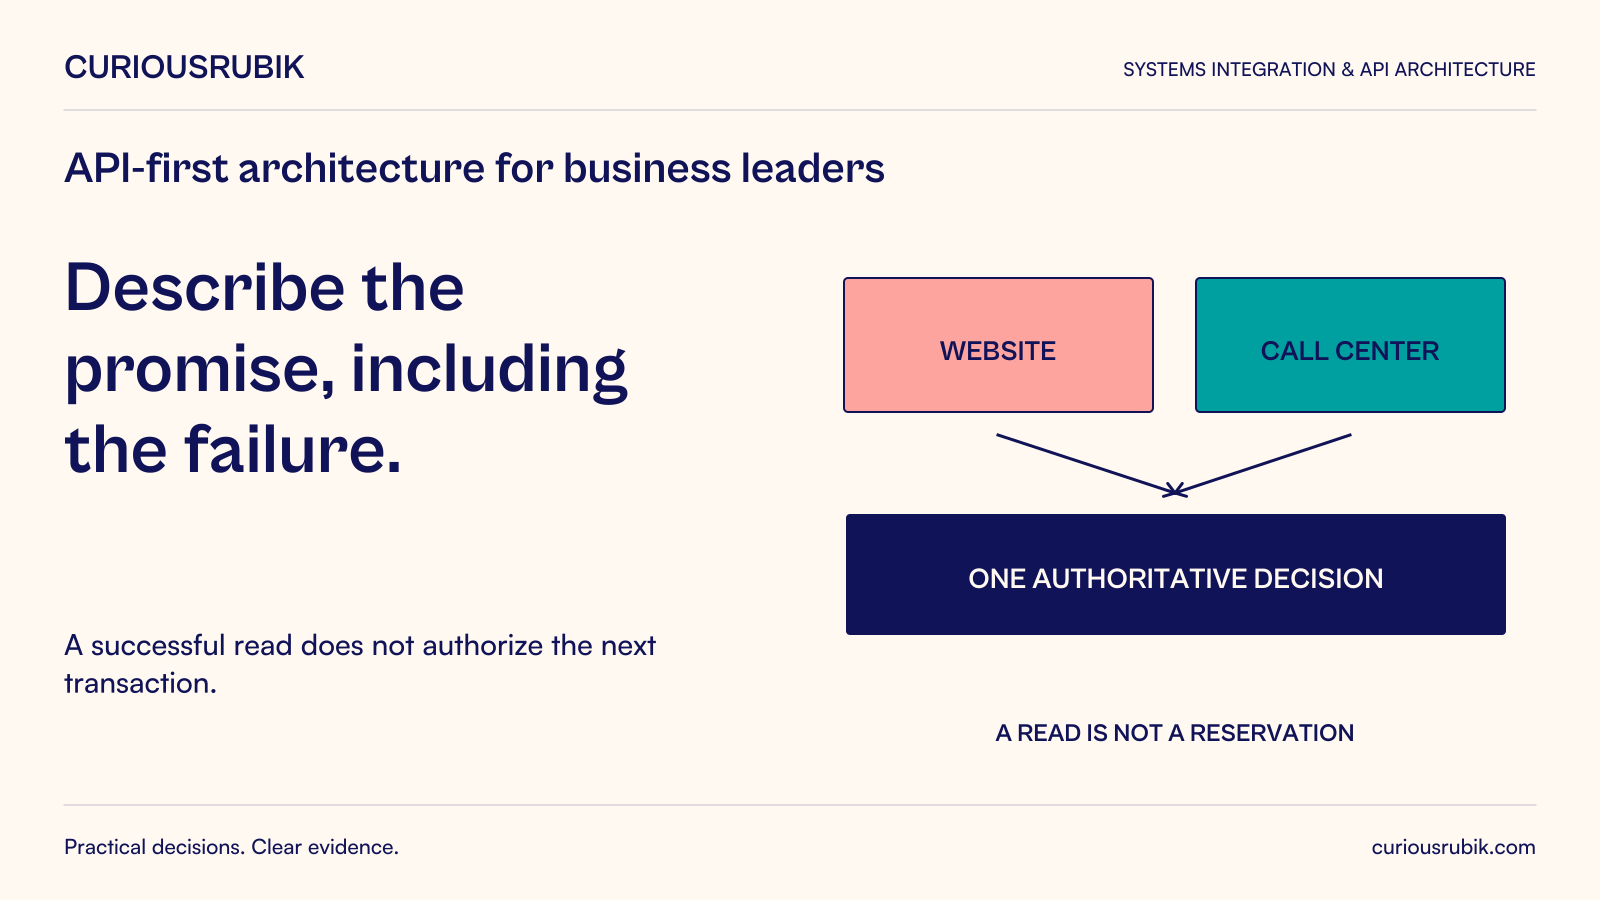
API-first architecture means agreeing and testing the interface consumers need before implementation choices make that interface expensive to change. The business value lies in clarifying capabilities, responsibilities, and failure …
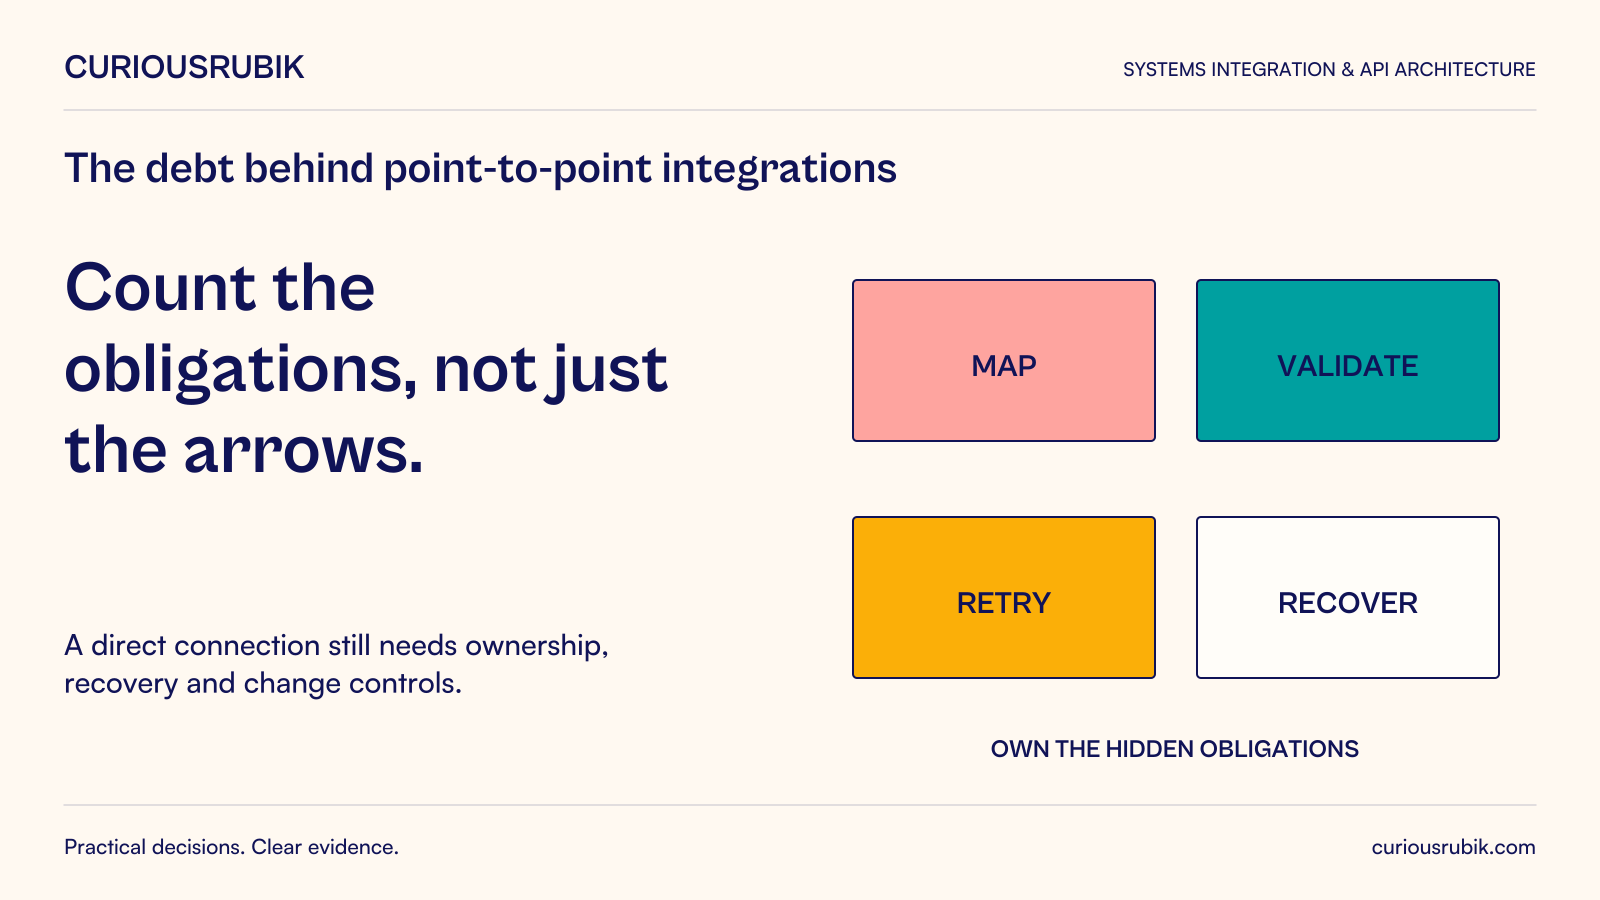
A direct integration becomes technical debt when its shortcuts repeatedly increase the cost or risk of changing the business. The number of connections alone does not establish that debt. A small, stable, well-owned connection can be …
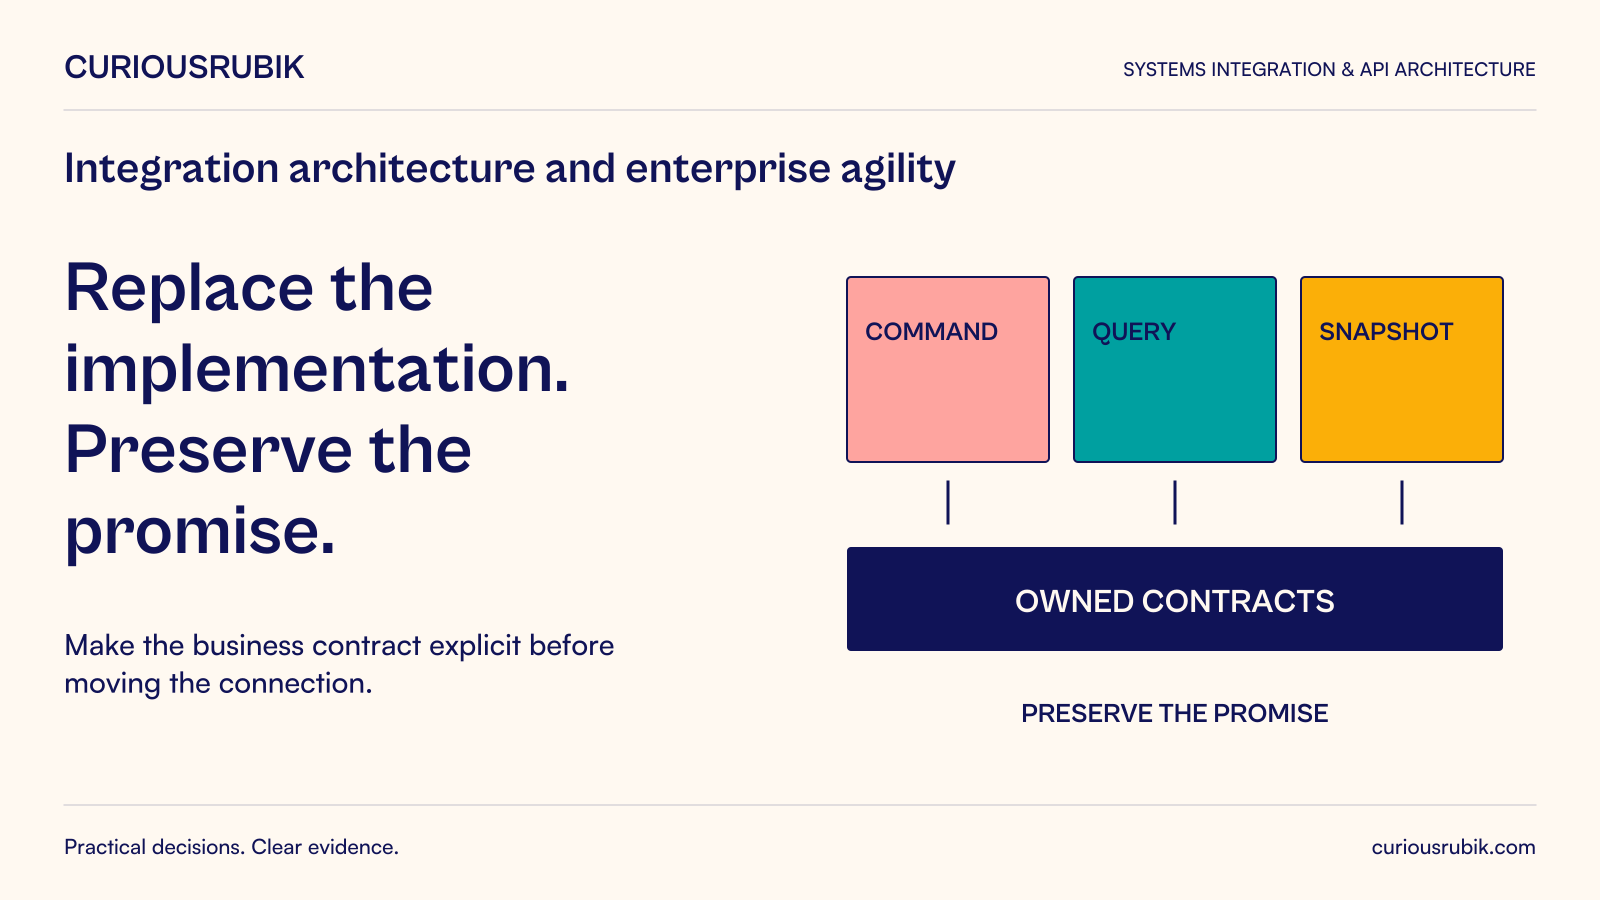
A stable business contract can make an application change easier by keeping consumers independent of the application’s internal representation. Integration architecture determines where that boundary exists, who owns it, and what happens …
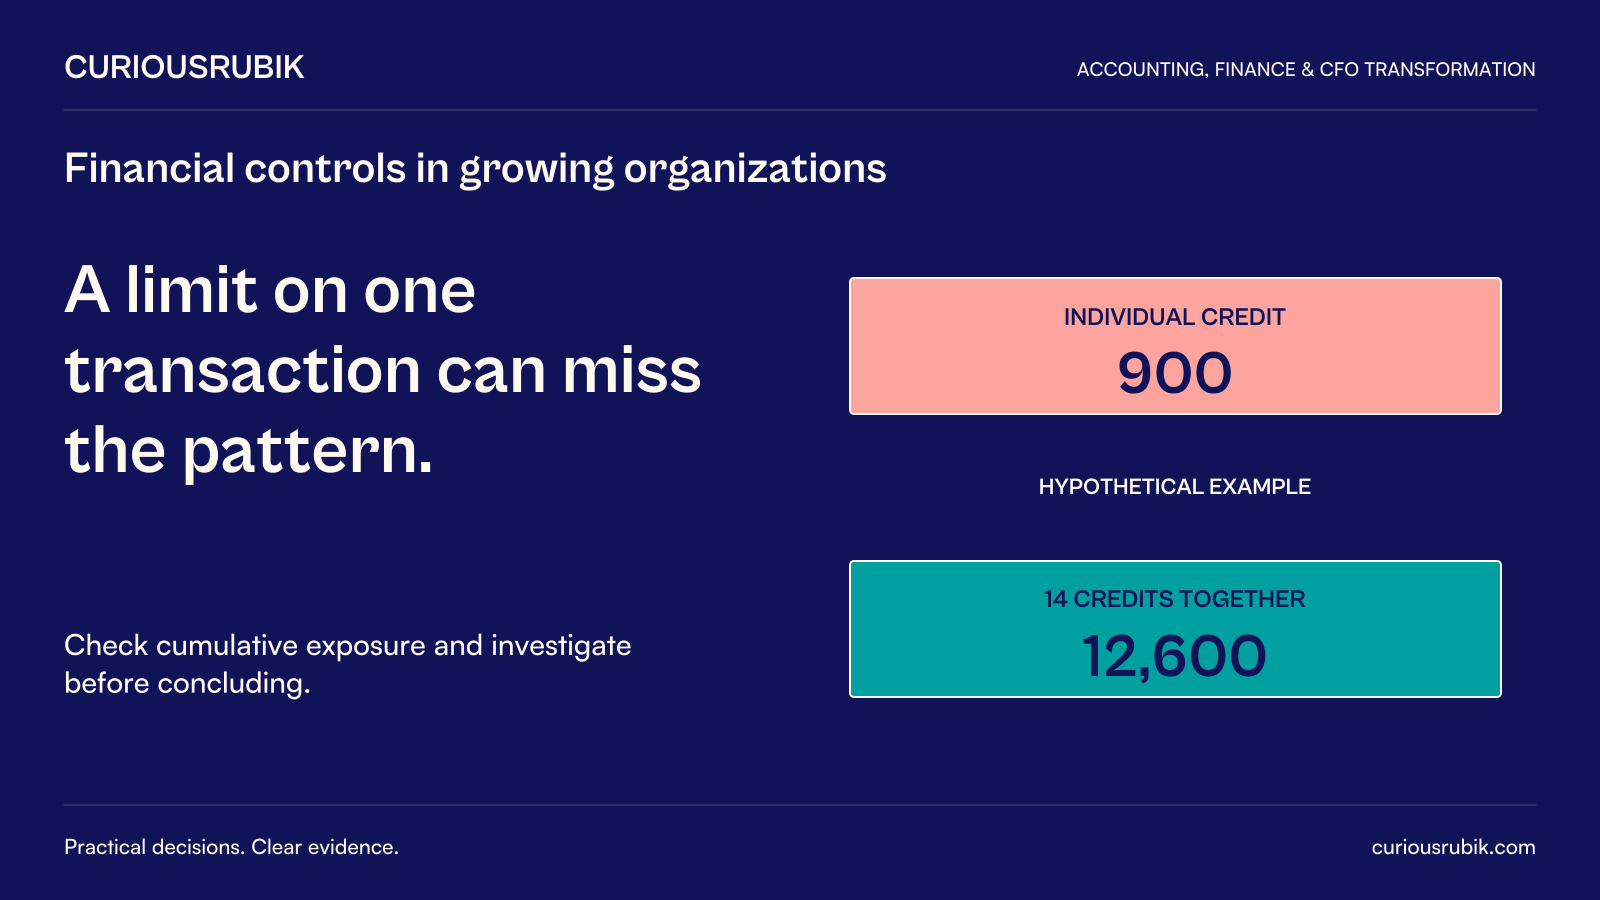
Financial controls scale when they address a defined risk at the point where useful evidence and appropriate authority are available. Adding approvals as transaction volume grows can create queues without improving the quality of …
Finance creates decision value when it connects reliable transaction records to an explicit explanation of the business choices available. More dashboards do not establish that connection. The important change is a disciplined route from …
Accounting leaders should redesign work around verifiable evidence, review capacity, and professional development before changing headcount assumptions around AI. A system that produces a plausible draft can reduce preparation effort while …
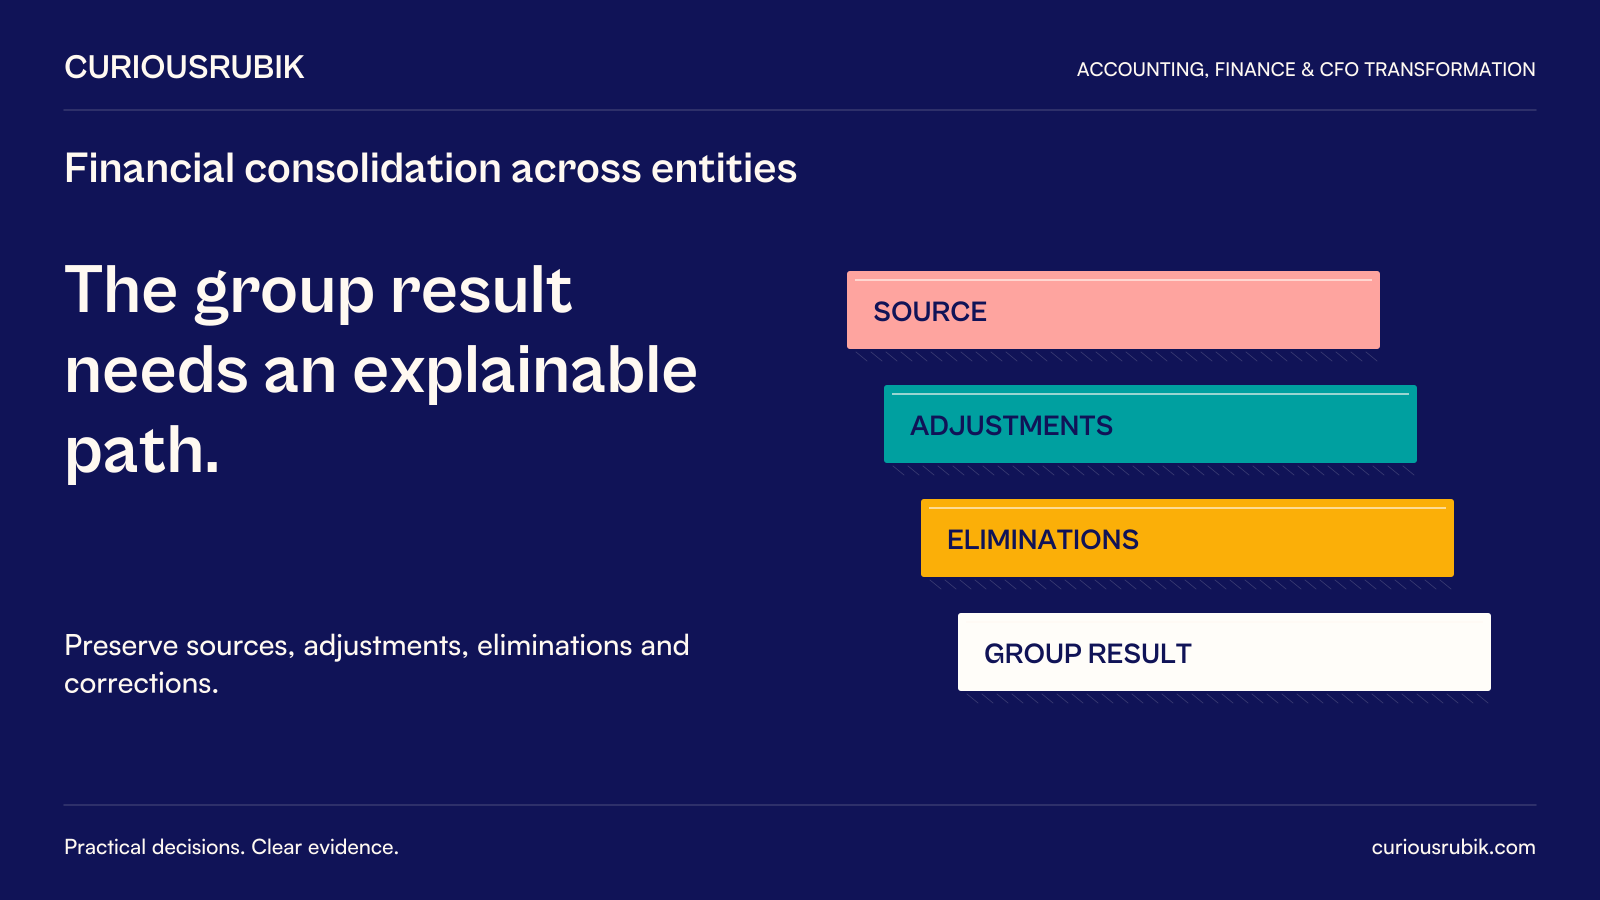
A group controller should treat consolidation as a controlled transformation of entity information into a group view. Adding trial balances is only the starting point. The difficult work is establishing the reporting perimeter, aligning …
Revenue recognition becomes difficult when the accounting team receives a billing total without the facts that explain what the customer was promised, what has been delivered, and what changed. Better integration should connect those facts …
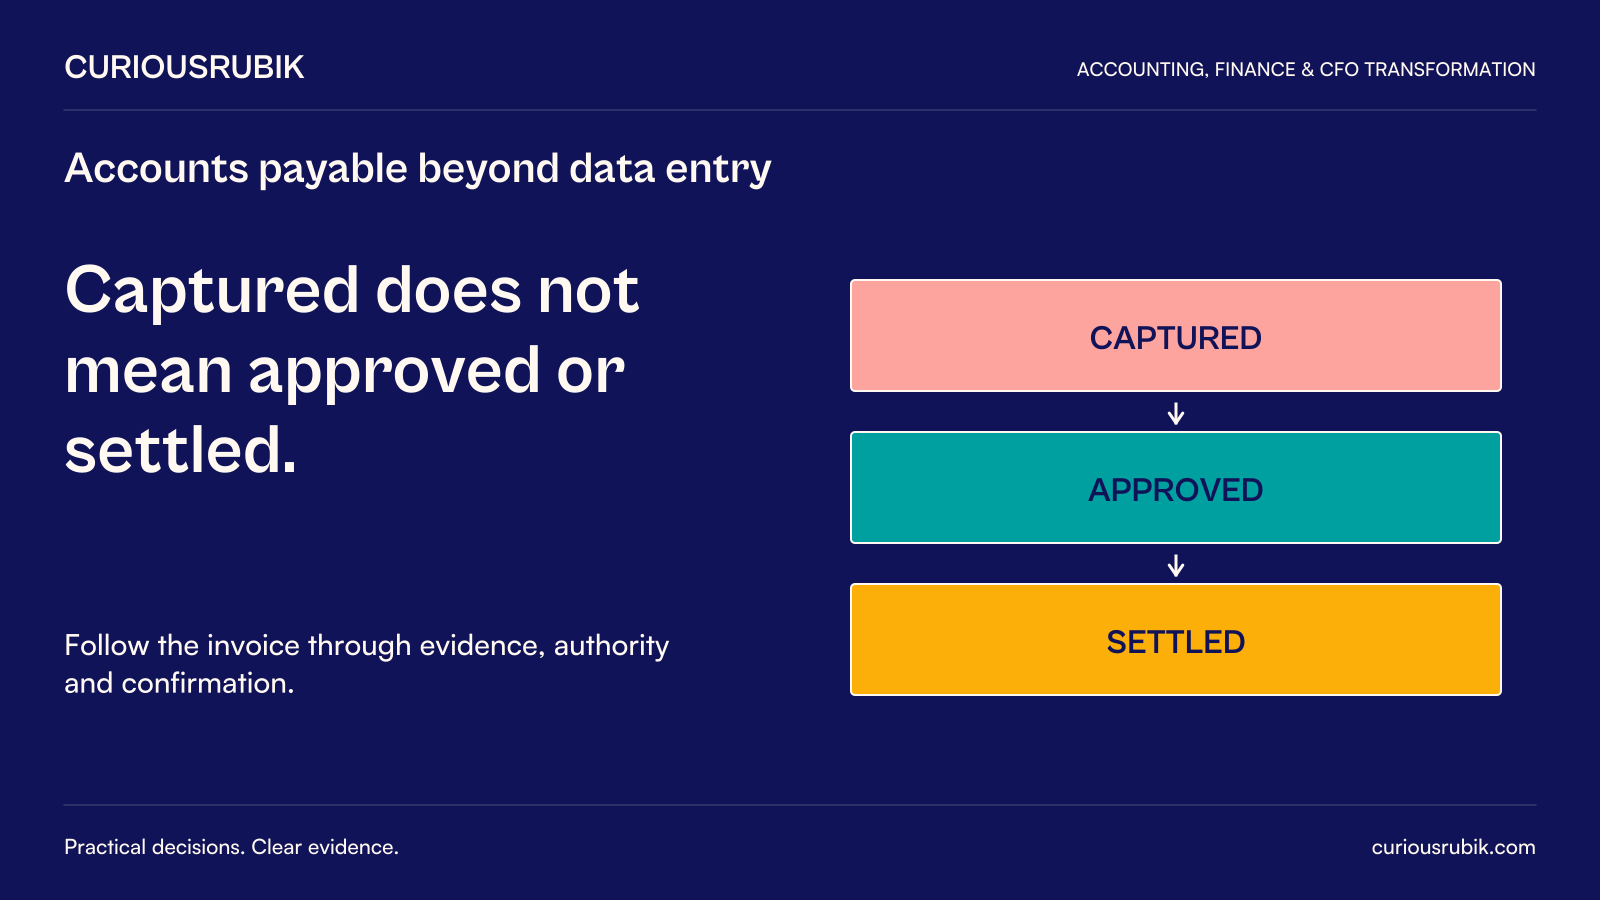
An accounts payable program should be designed around a controlled path from an authorized purchase to a correctly settled obligation. Reading an invoice is one step in that path. If the supplier record is unreliable, the receipt is …
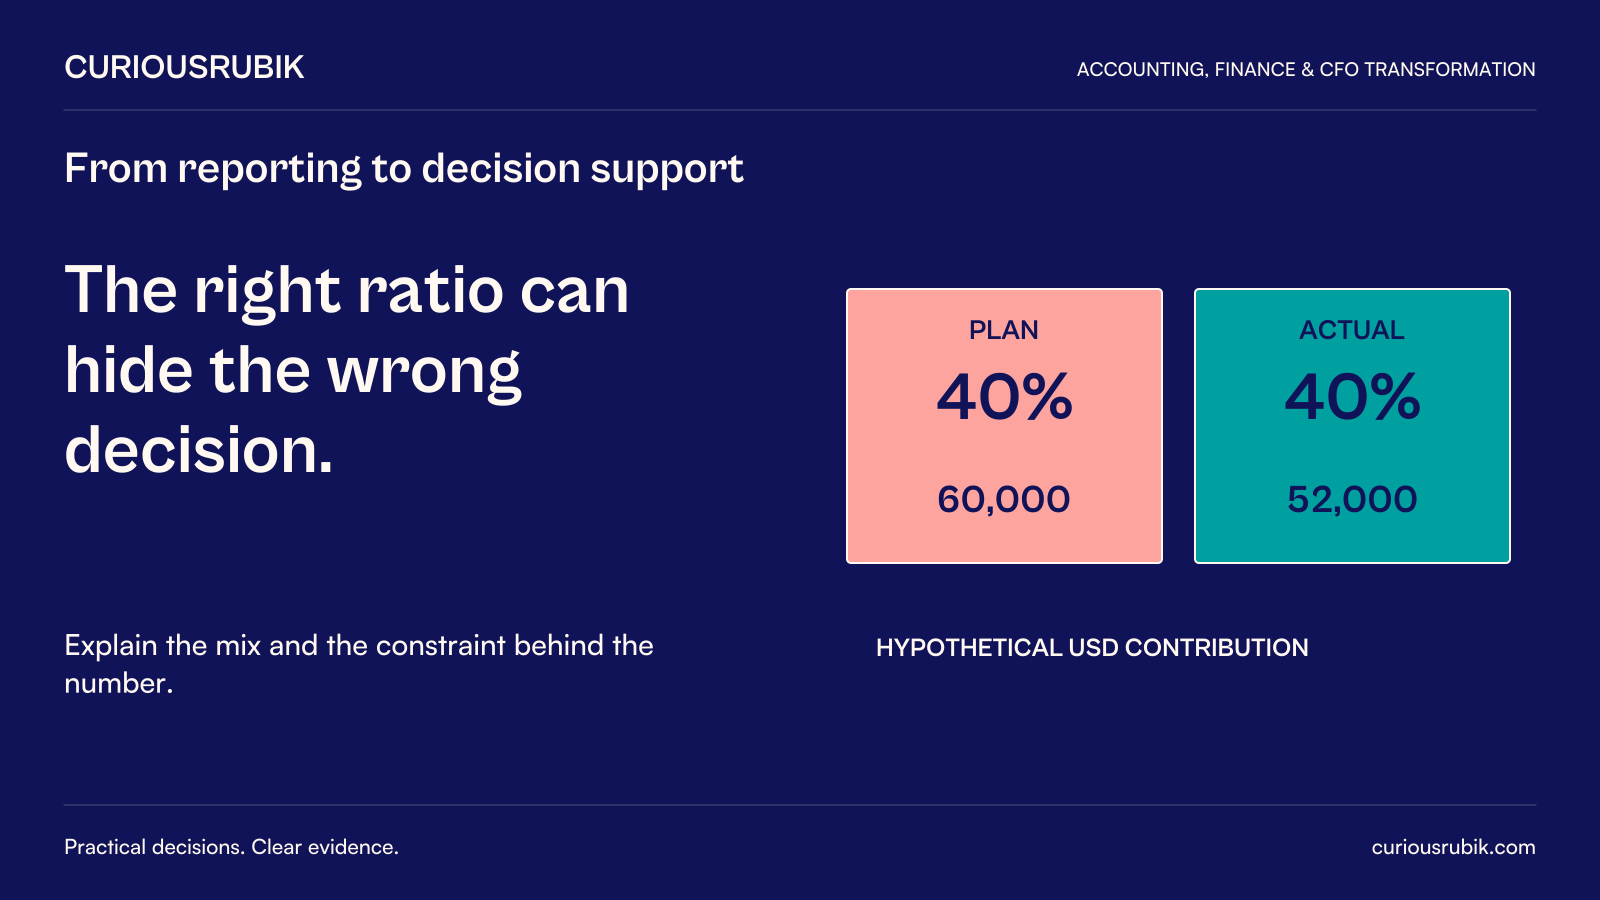
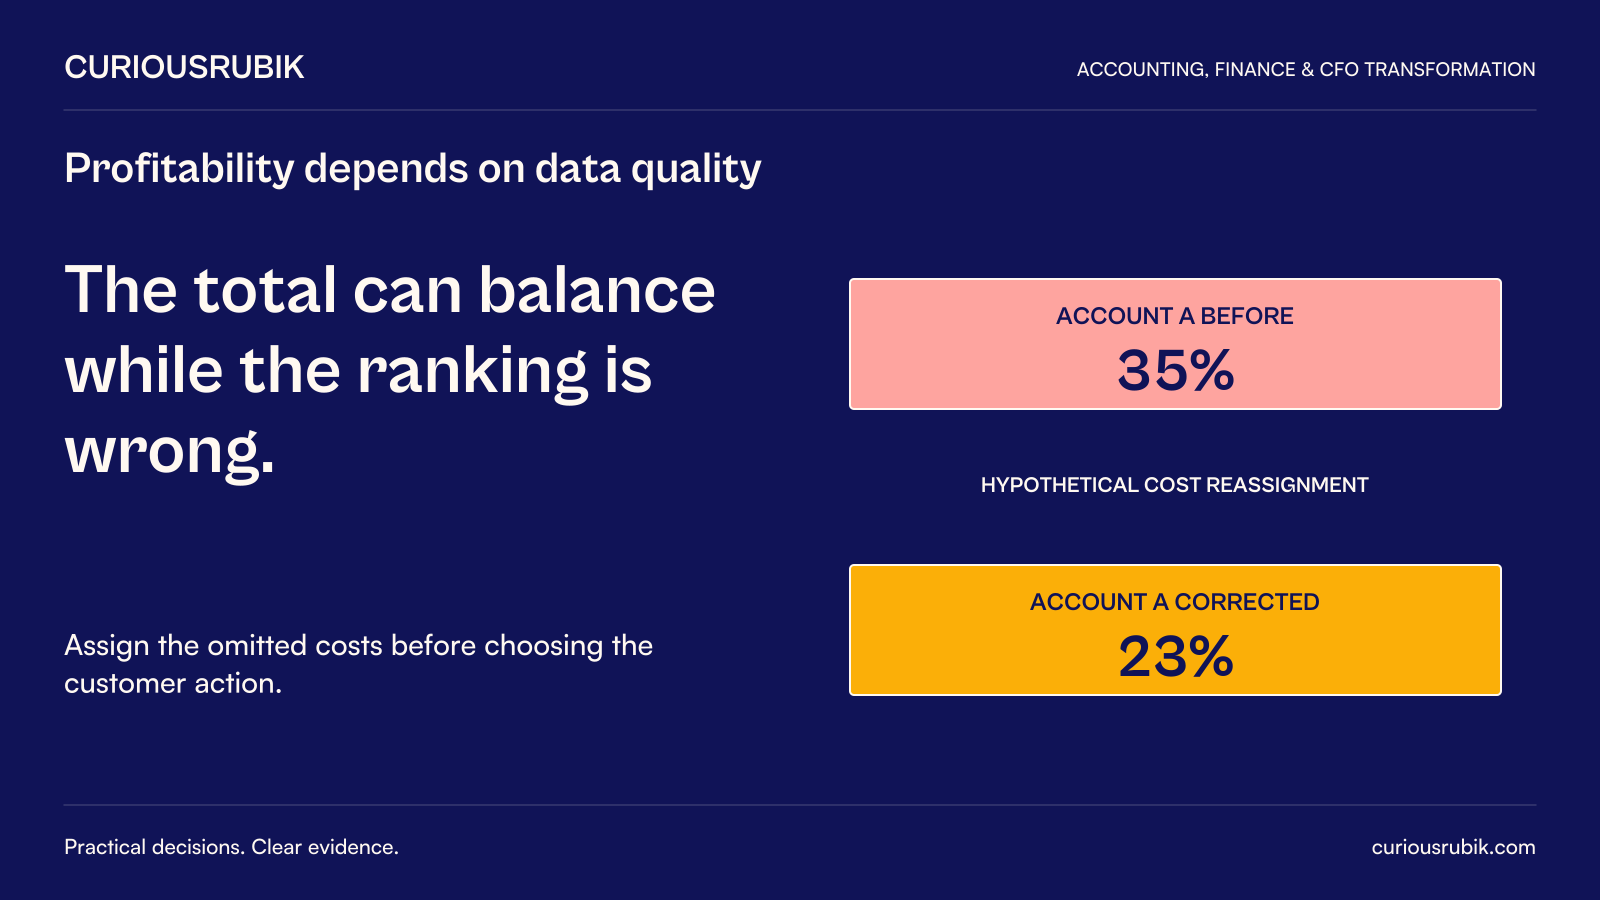
Financial data quality should be judged partly by whether an error can change the decision being made. A perfectly reconciled company total can still mislead an executive if costs are assigned to the wrong customer, a forecast mixes …
API-first architecture means agreeing and testing the interface consumers need before implementation choices make that interface expensive to change. The business value lies in clarifying capabilities, responsibilities, and failure …
A direct integration becomes technical debt when its shortcuts repeatedly increase the cost or risk of changing the business. The number of connections alone does not establish that debt. A small, stable, well-owned connection can be …
A stable business contract can make an application change easier by keeping consumers independent of the application’s internal representation. Integration architecture determines where that boundary exists, who owns it, and what happens …
Financial controls scale when they address a defined risk at the point where useful evidence and appropriate authority are available. Adding approvals as transaction volume grows can create queues without improving the quality of …
Finance creates decision value when it connects reliable transaction records to an explicit explanation of the business choices available. More dashboards do not establish that connection. The important change is a disciplined route from …
Accounting leaders should redesign work around verifiable evidence, review capacity, and professional development before changing headcount assumptions around AI. A system that produces a plausible draft can reduce preparation effort while …
A group controller should treat consolidation as a controlled transformation of entity information into a group view. Adding trial balances is only the starting point. The difficult work is establishing the reporting perimeter, aligning …
Revenue recognition becomes difficult when the accounting team receives a billing total without the facts that explain what the customer was promised, what has been delivered, and what changed. Better integration should connect those facts …
An accounts payable program should be designed around a controlled path from an authorized purchase to a correctly settled obligation. Reading an invoice is one step in that path. If the supplier record is unreliable, the receipt is …
Financial data quality should be judged partly by whether an error can change the decision being made. A perfectly reconciled company total can still mislead an executive if costs are assigned to the wrong customer, a forecast mixes …