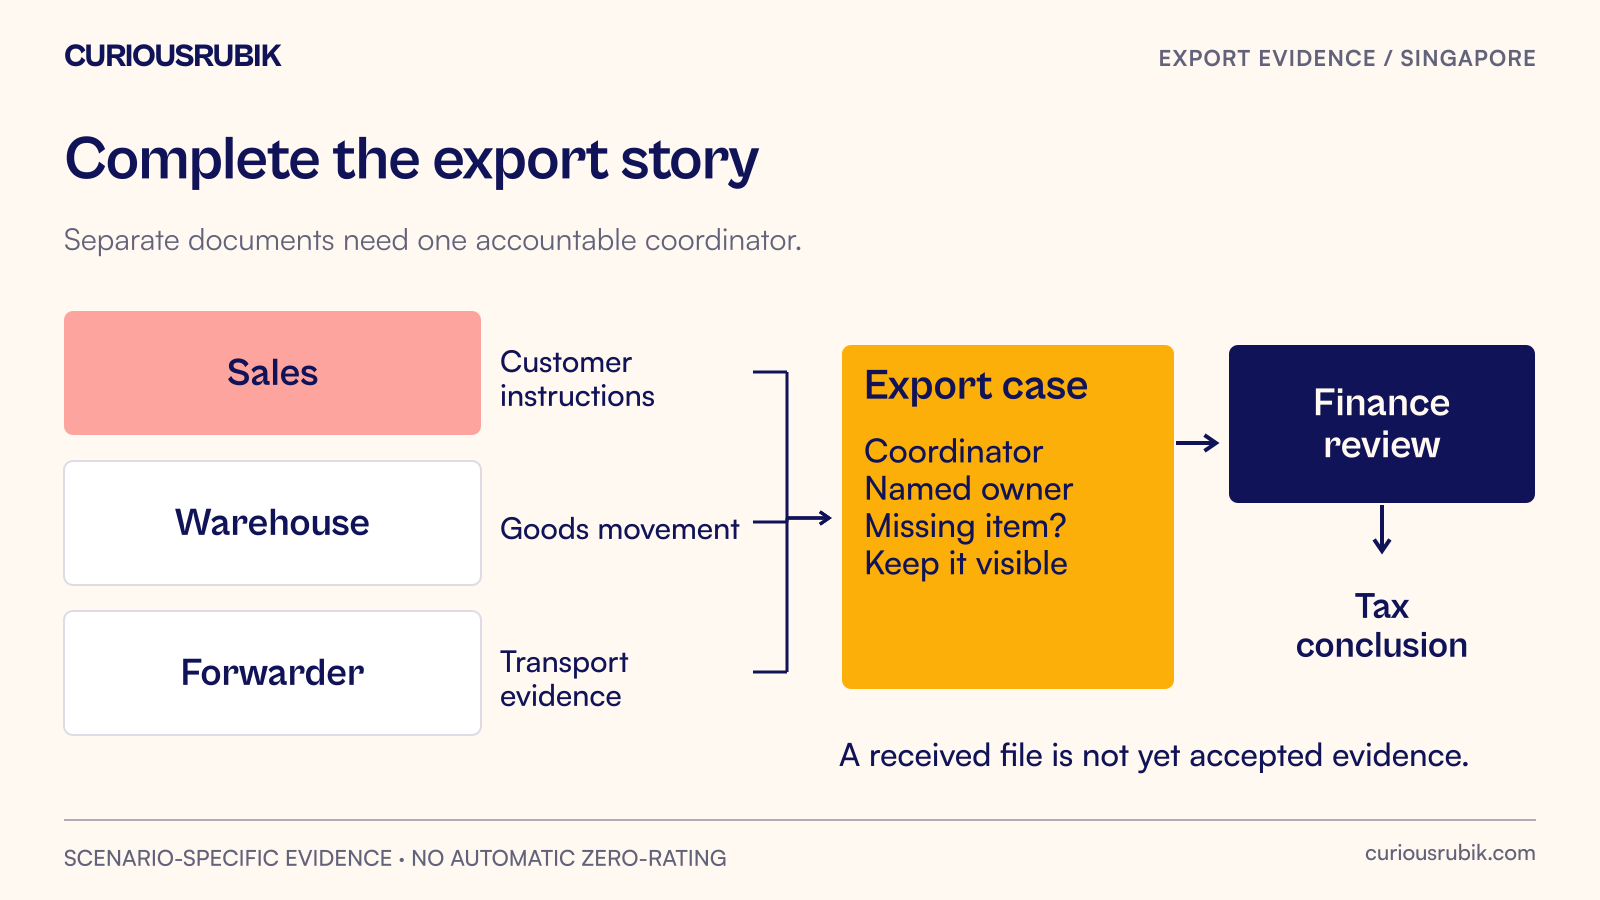
Sales holds the order. The warehouse has the collection note. The freight forwarder has the transport record. Finance sees an overseas customer and an invoice marked for export, but nobody can say whether the evidence set is complete.
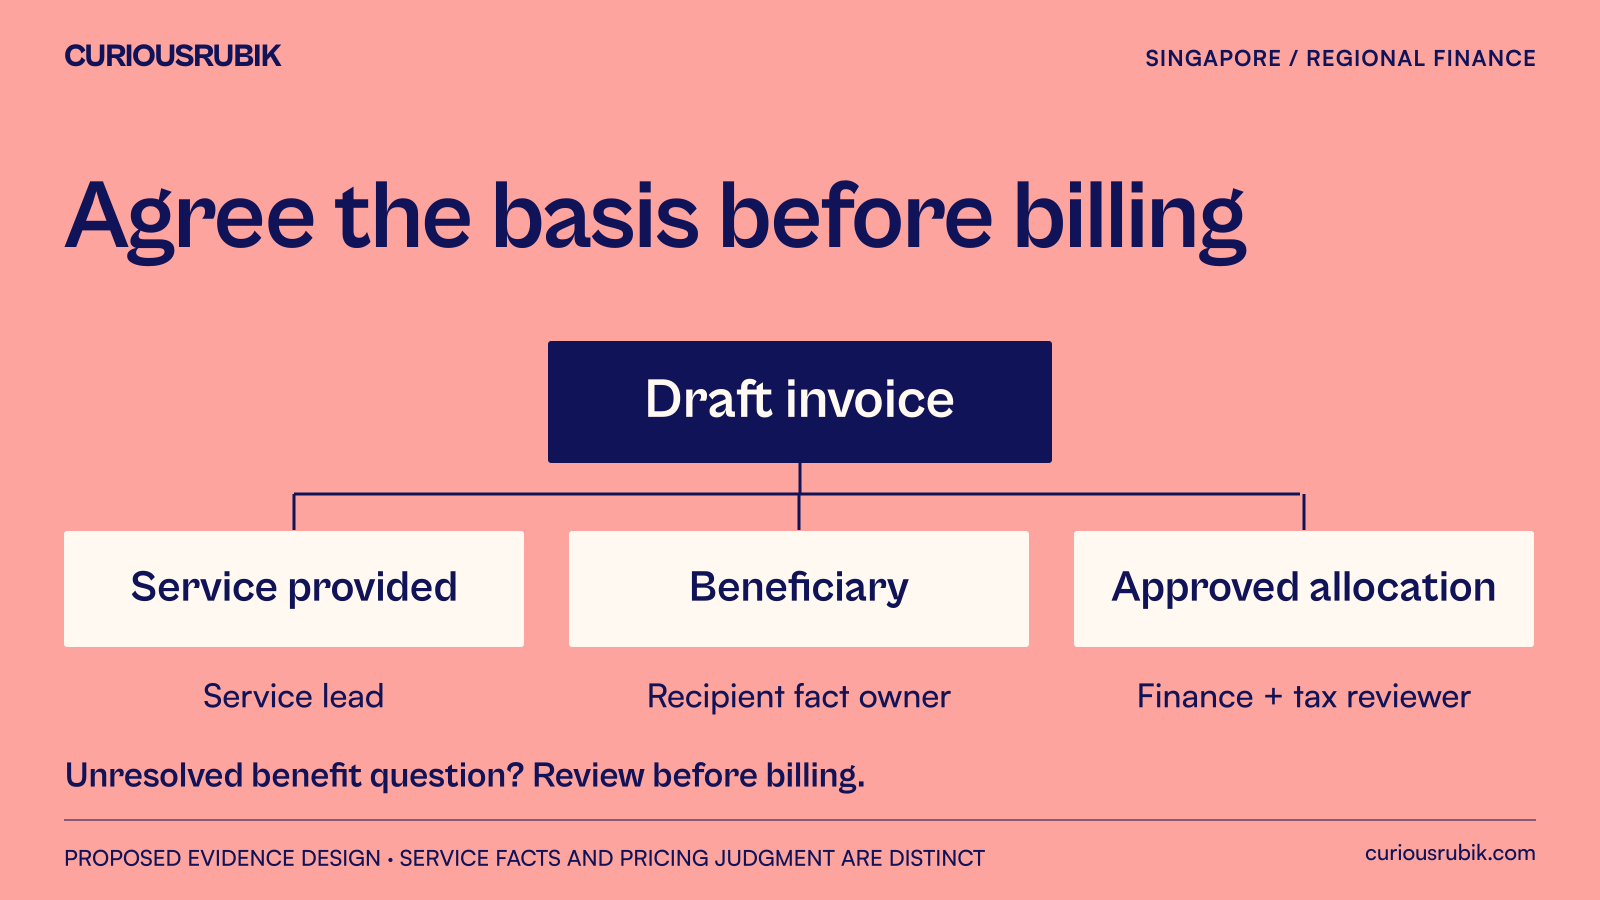
A regional office can calculate a recharge perfectly and still produce an invoice that the recipient disputes. The recipient may question whether it received the service, why a particular cost was included or why headcount was used to …
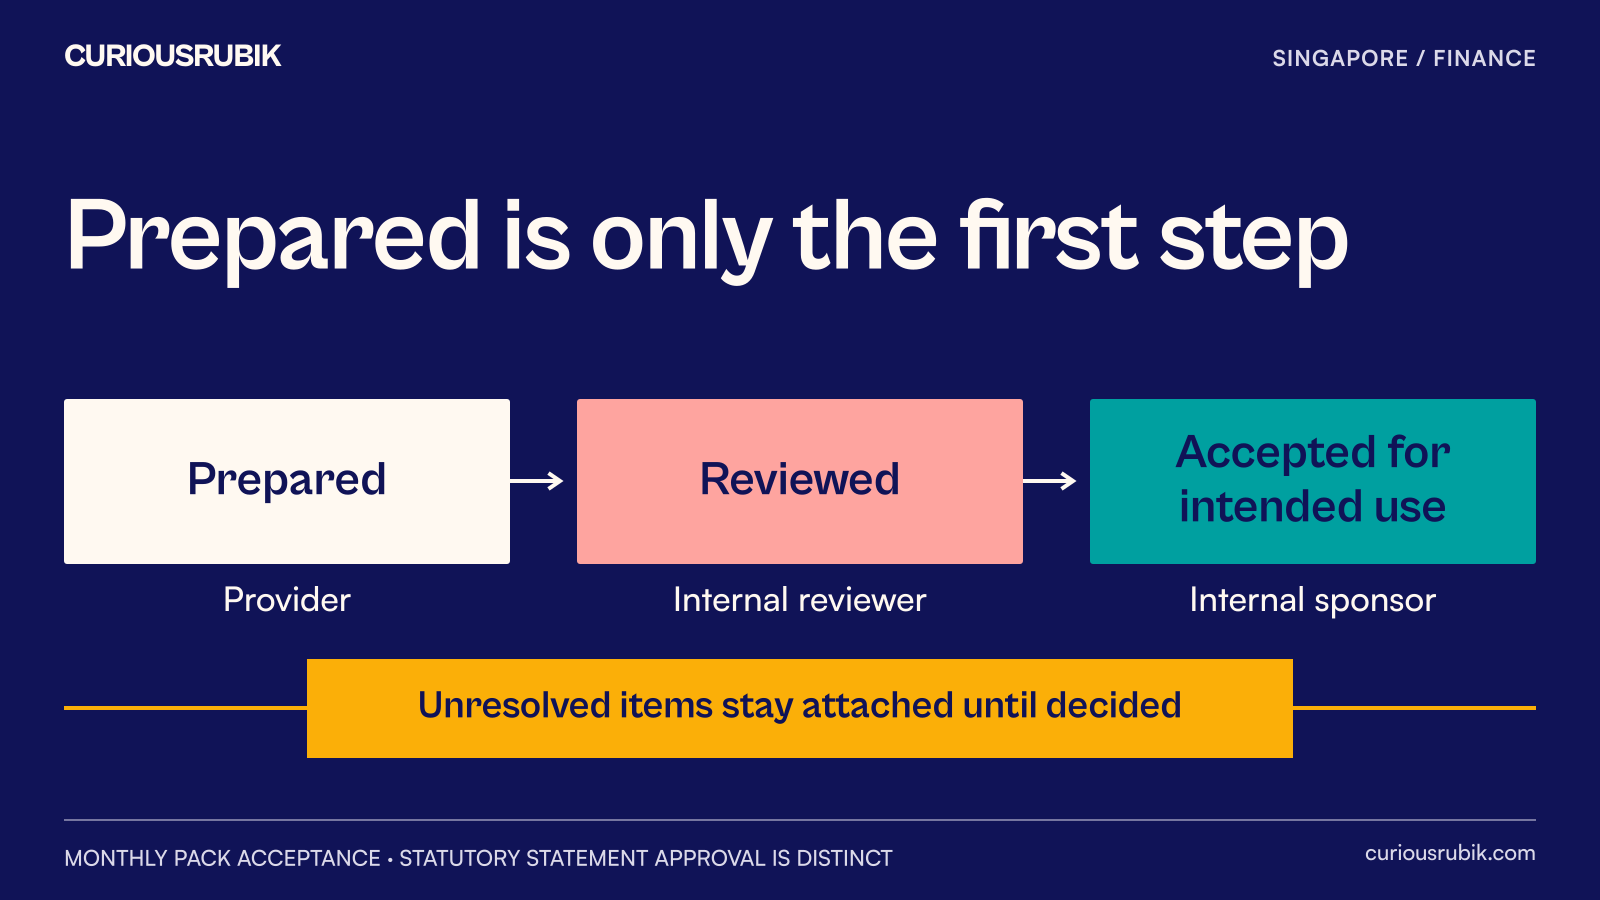
The accounting provider has delivered the monthly pack. The bank reconciliation is attached, the schedules are neatly labelled and the profit figure is available for management's meeting. One balance still has no explanation, and two …
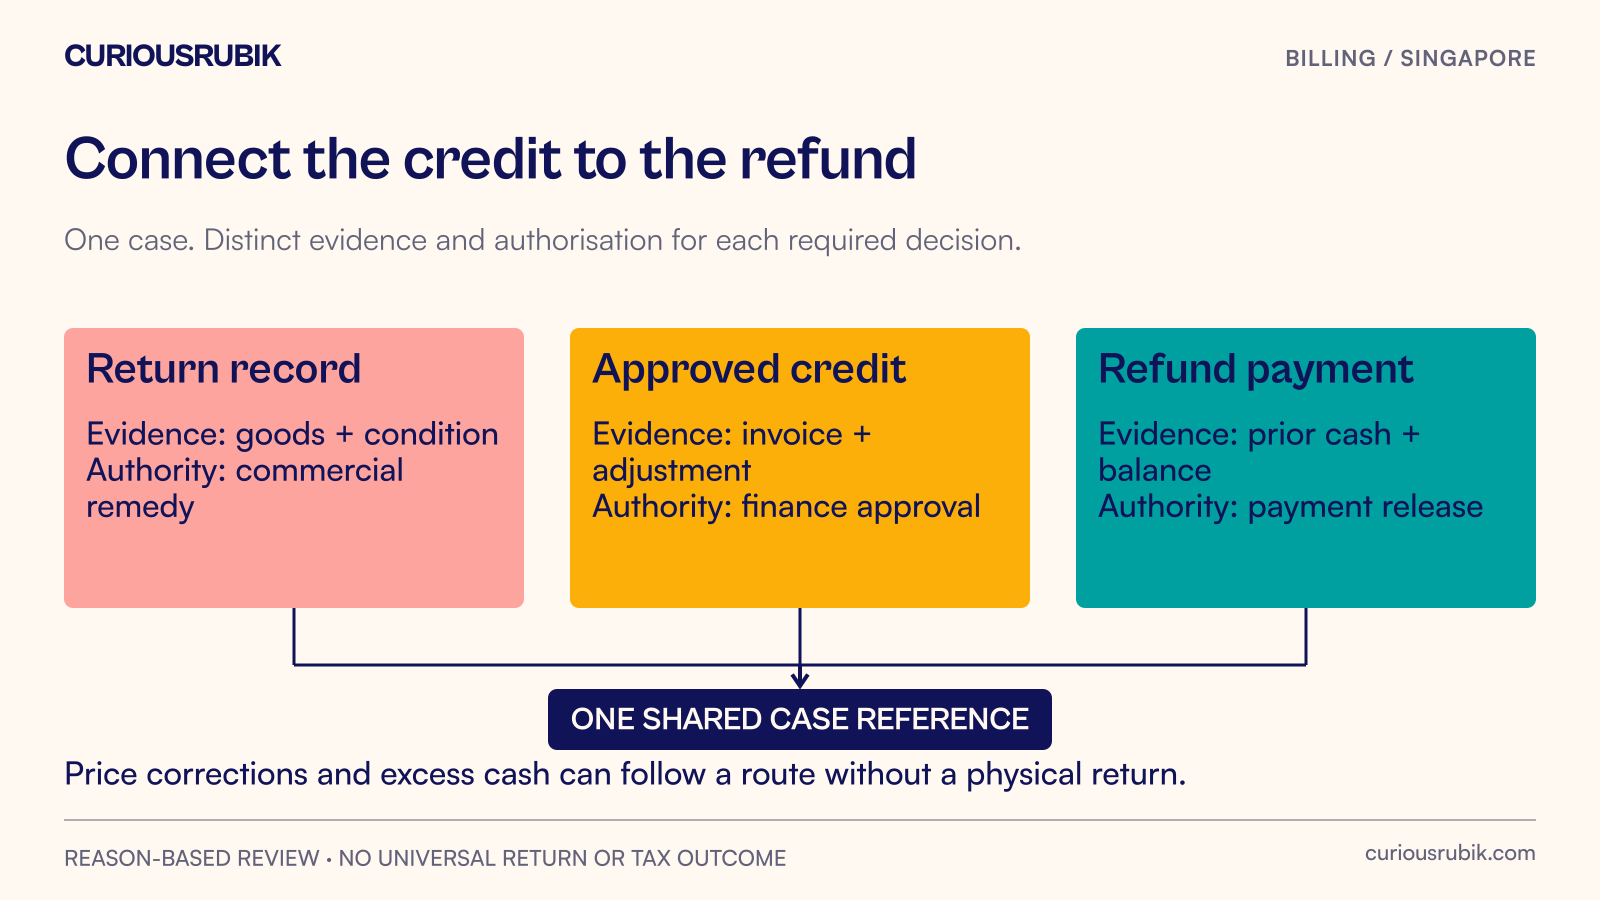
A customer service colleague promises a refund. The warehouse is waiting for the goods, finance has not approved the adjustment and the payment team receives a new bank account in an email. The customer sees one request; the business has …
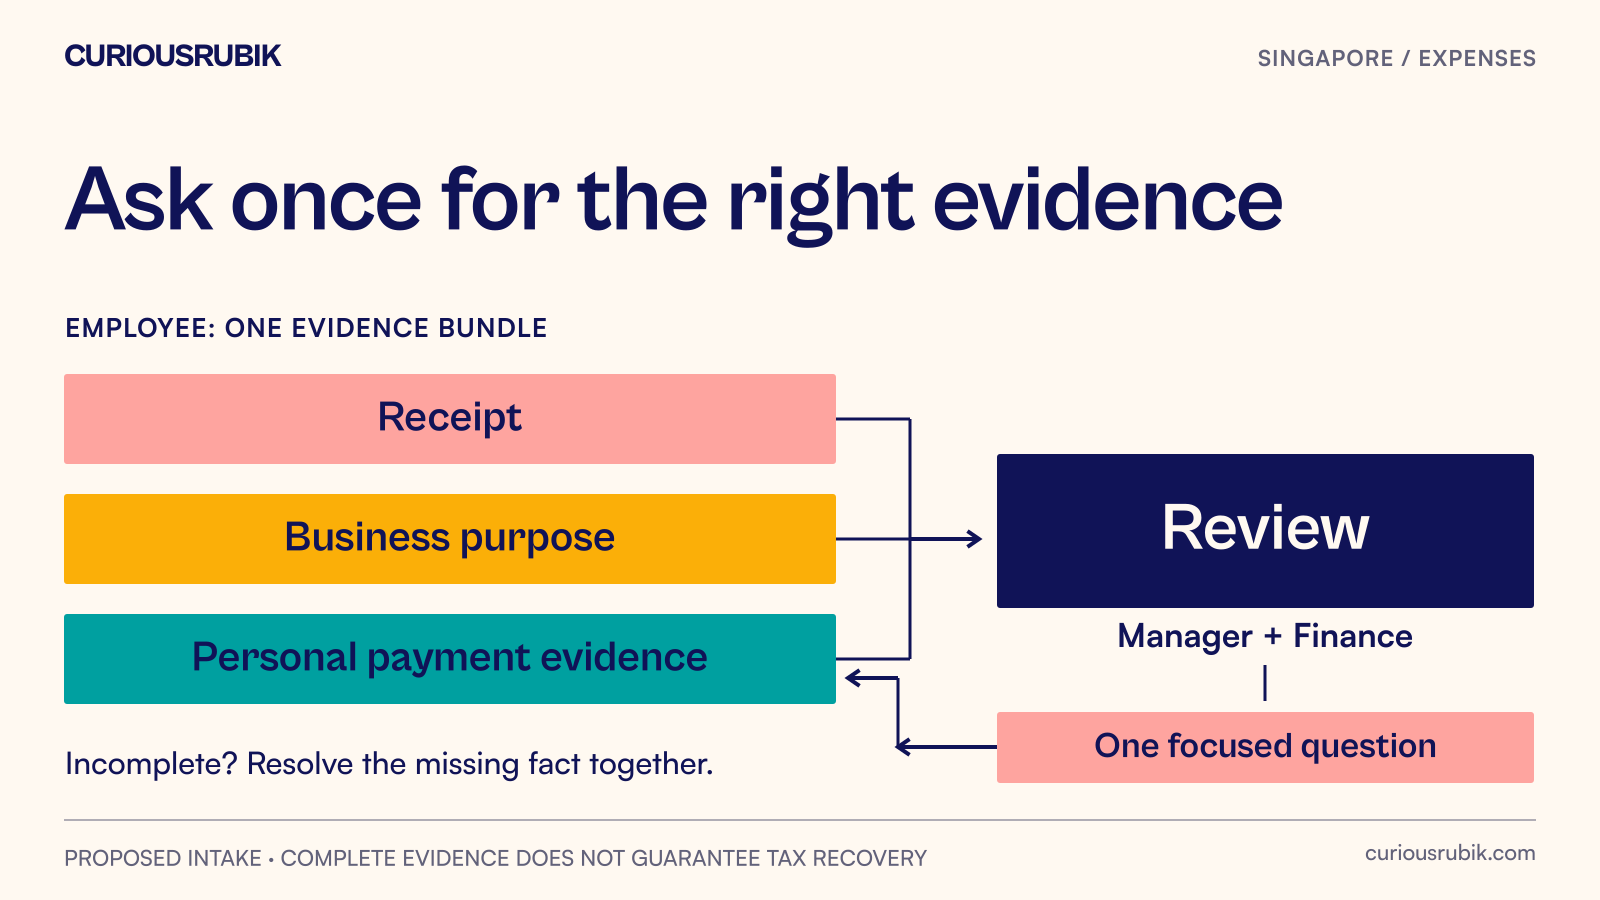
An employee submits a receipt. Finance asks for the business purpose. The manager approves it. Finance then asks whether the employee paid personally, whether part of the bill was private and whether a clearer copy exists. By the time the …
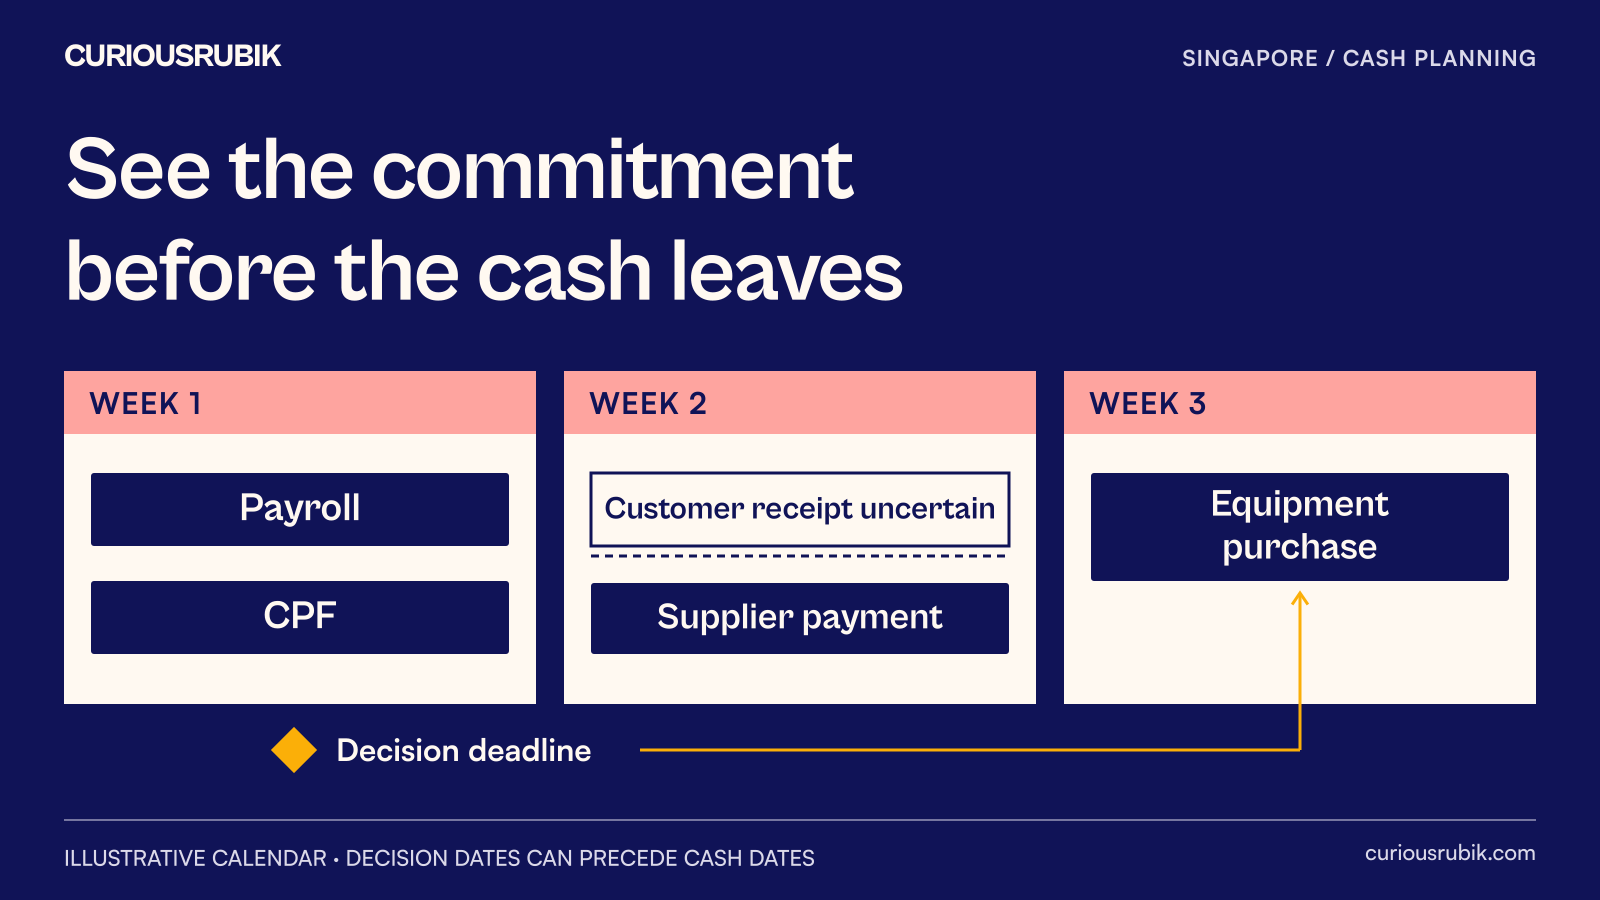
A forecast can show a comfortable closing balance while hiding the decision that will make next week's balance uncomfortable. The missing information is often the date on which a purchase, contract or delivery commitment becomes difficult …
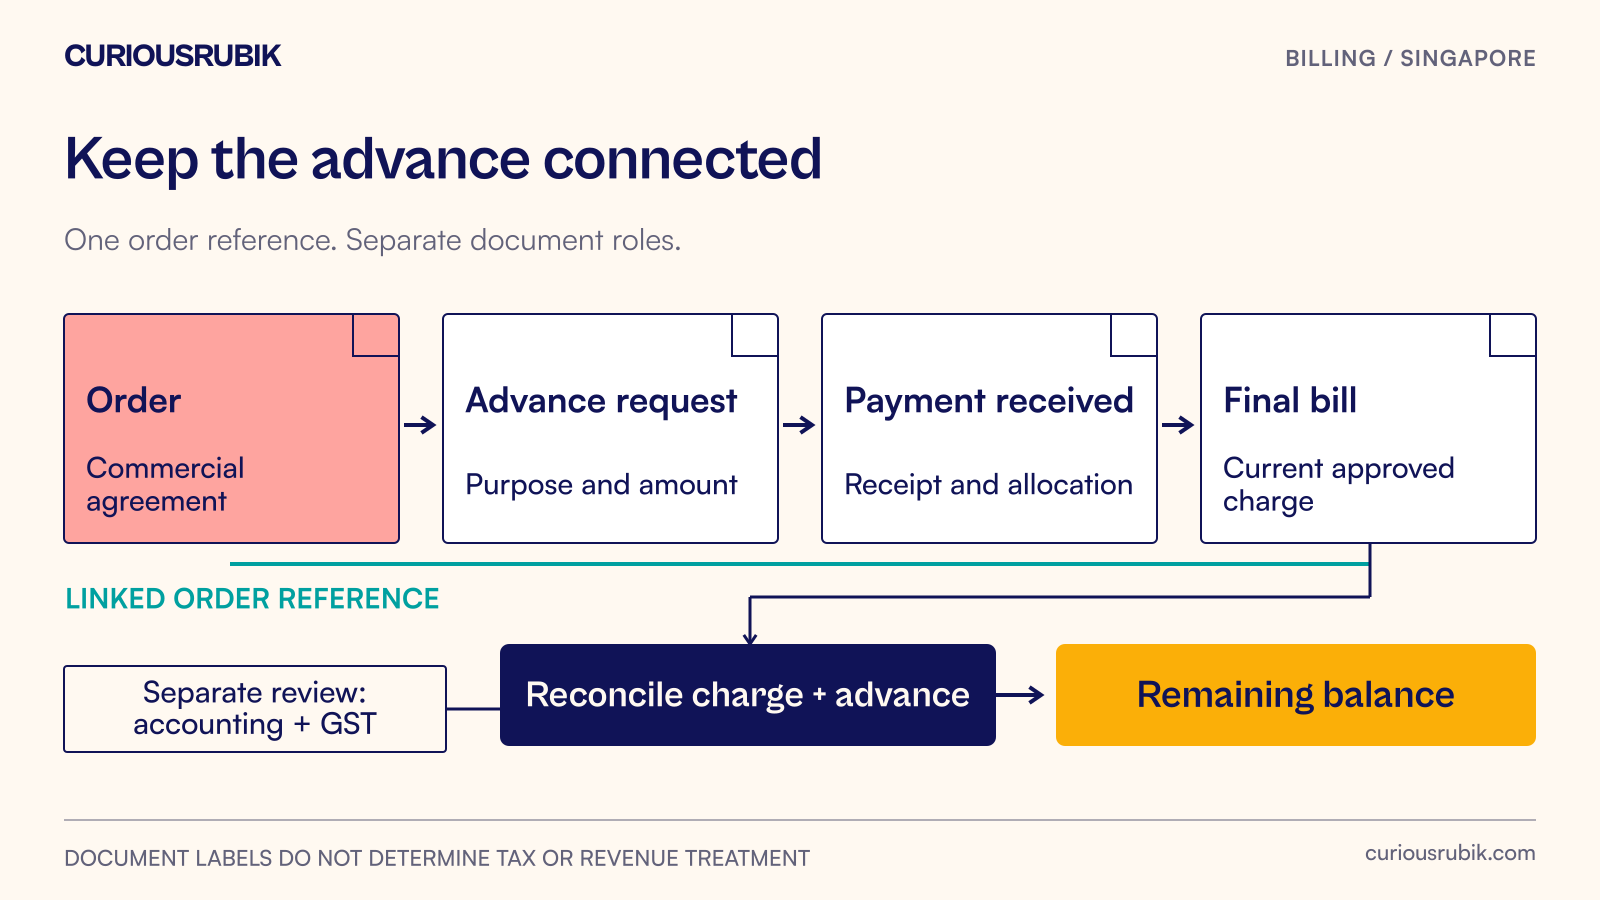
The customer has already paid an advance. The final invoice is issued for the full order, and the collections team asks for the full amount again. Nobody intended to double bill: the payment sits in one list, the advance request in another …
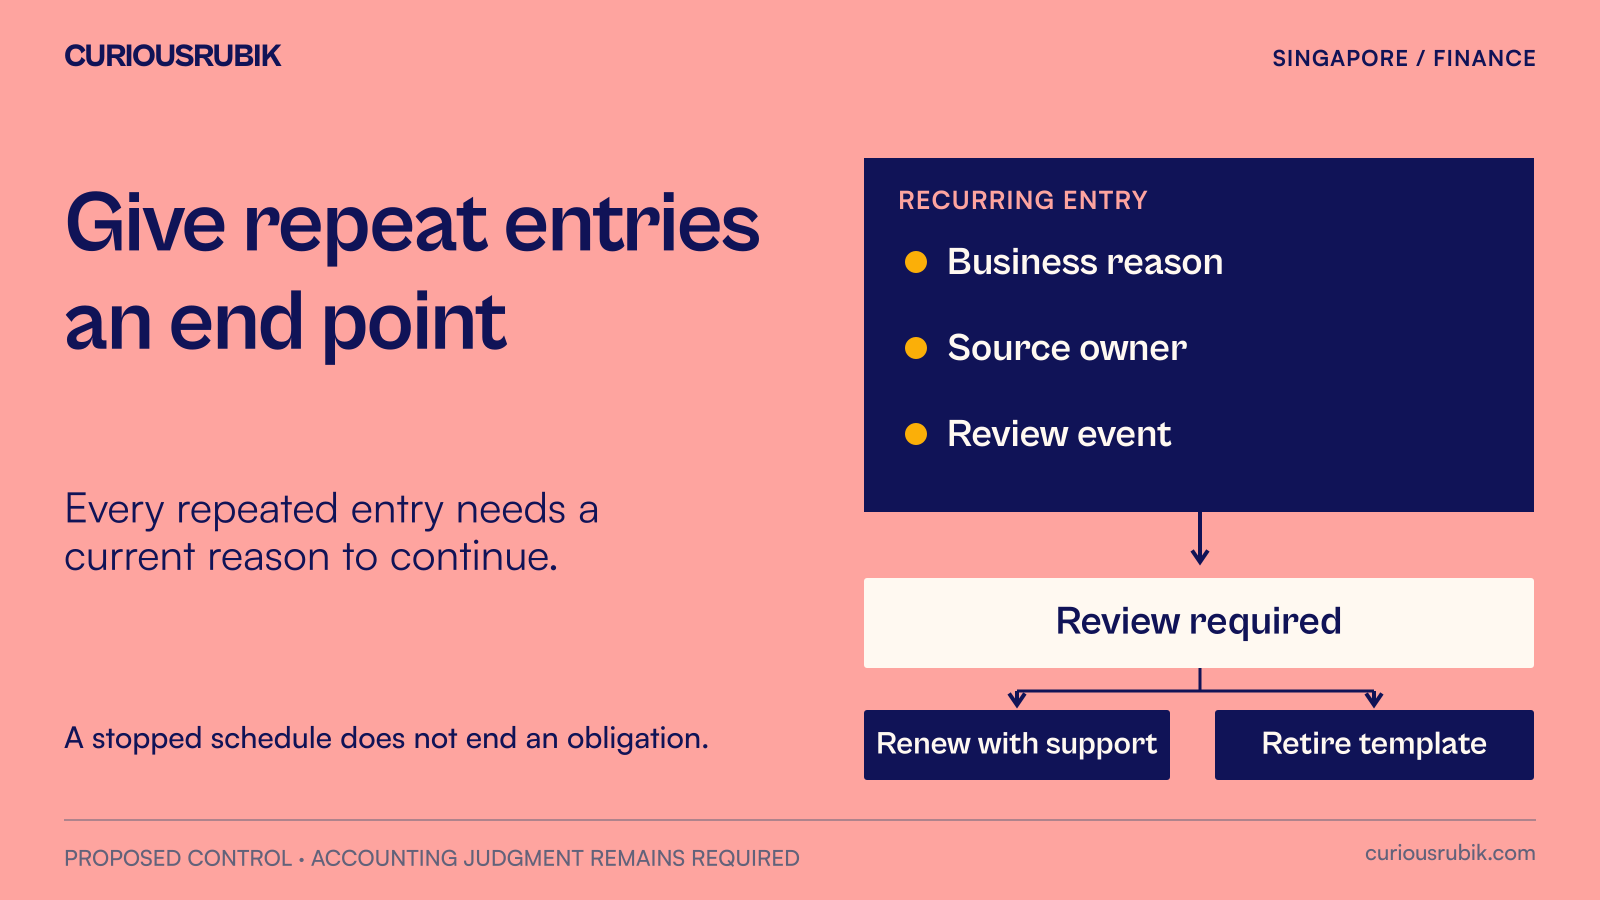
A monthly journal can keep running long after the reason for it has changed. The amount looks familiar, the description matches last month and the reviewer has more unusual items to investigate. That familiarity is precisely why a …
Sales holds the order. The warehouse has the collection note. The freight forwarder has the transport record. Finance sees an overseas customer and an invoice marked for export, but nobody can say whether the evidence set is complete.
A regional office can calculate a recharge perfectly and still produce an invoice that the recipient disputes. The recipient may question whether it received the service, why a particular cost was included or why headcount was used to …
The accounting provider has delivered the monthly pack. The bank reconciliation is attached, the schedules are neatly labelled and the profit figure is available for management's meeting. One balance still has no explanation, and two …
A customer service colleague promises a refund. The warehouse is waiting for the goods, finance has not approved the adjustment and the payment team receives a new bank account in an email. The customer sees one request; the business has …
An employee submits a receipt. Finance asks for the business purpose. The manager approves it. Finance then asks whether the employee paid personally, whether part of the bill was private and whether a clearer copy exists. By the time the …
A forecast can show a comfortable closing balance while hiding the decision that will make next week's balance uncomfortable. The missing information is often the date on which a purchase, contract or delivery commitment becomes difficult …
The customer has already paid an advance. The final invoice is issued for the full order, and the collections team asks for the full amount again. Nobody intended to double bill: the payment sits in one list, the advance request in another …
A monthly journal can keep running long after the reason for it has changed. The amount looks familiar, the description matches last month and the reviewer has more unusual items to investigate. That familiarity is precisely why a …