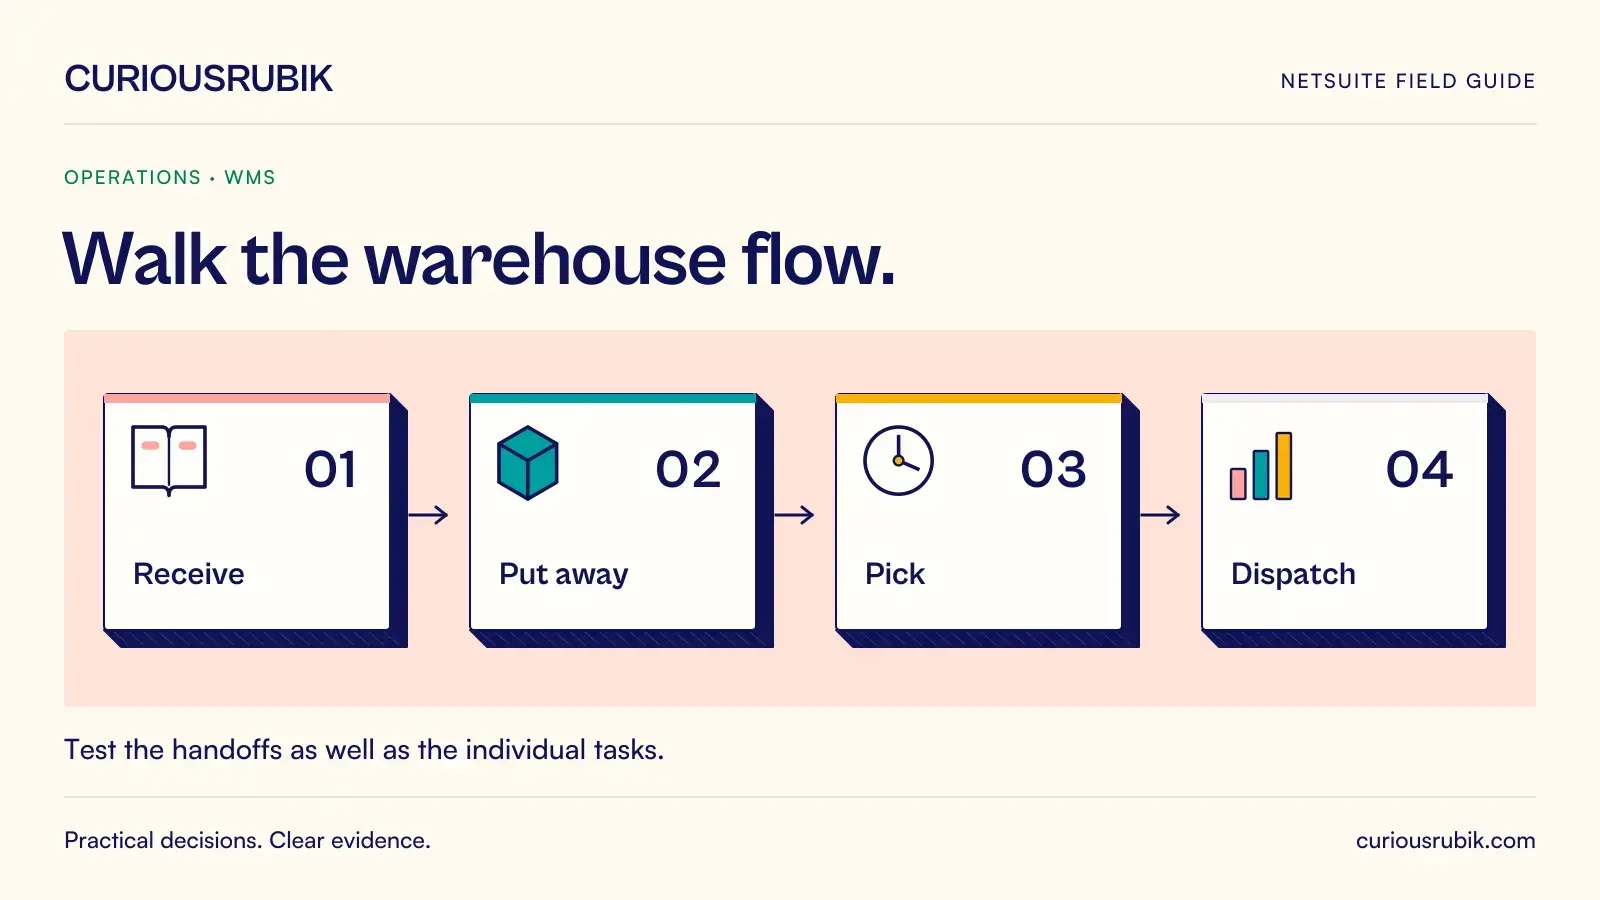
A warehouse management demonstration can look convincing when every label scans, every bin contains the expected quantity, and the order ships in full. Daily operations are less orderly. Receipts arrive short, stock appears in the wrong …
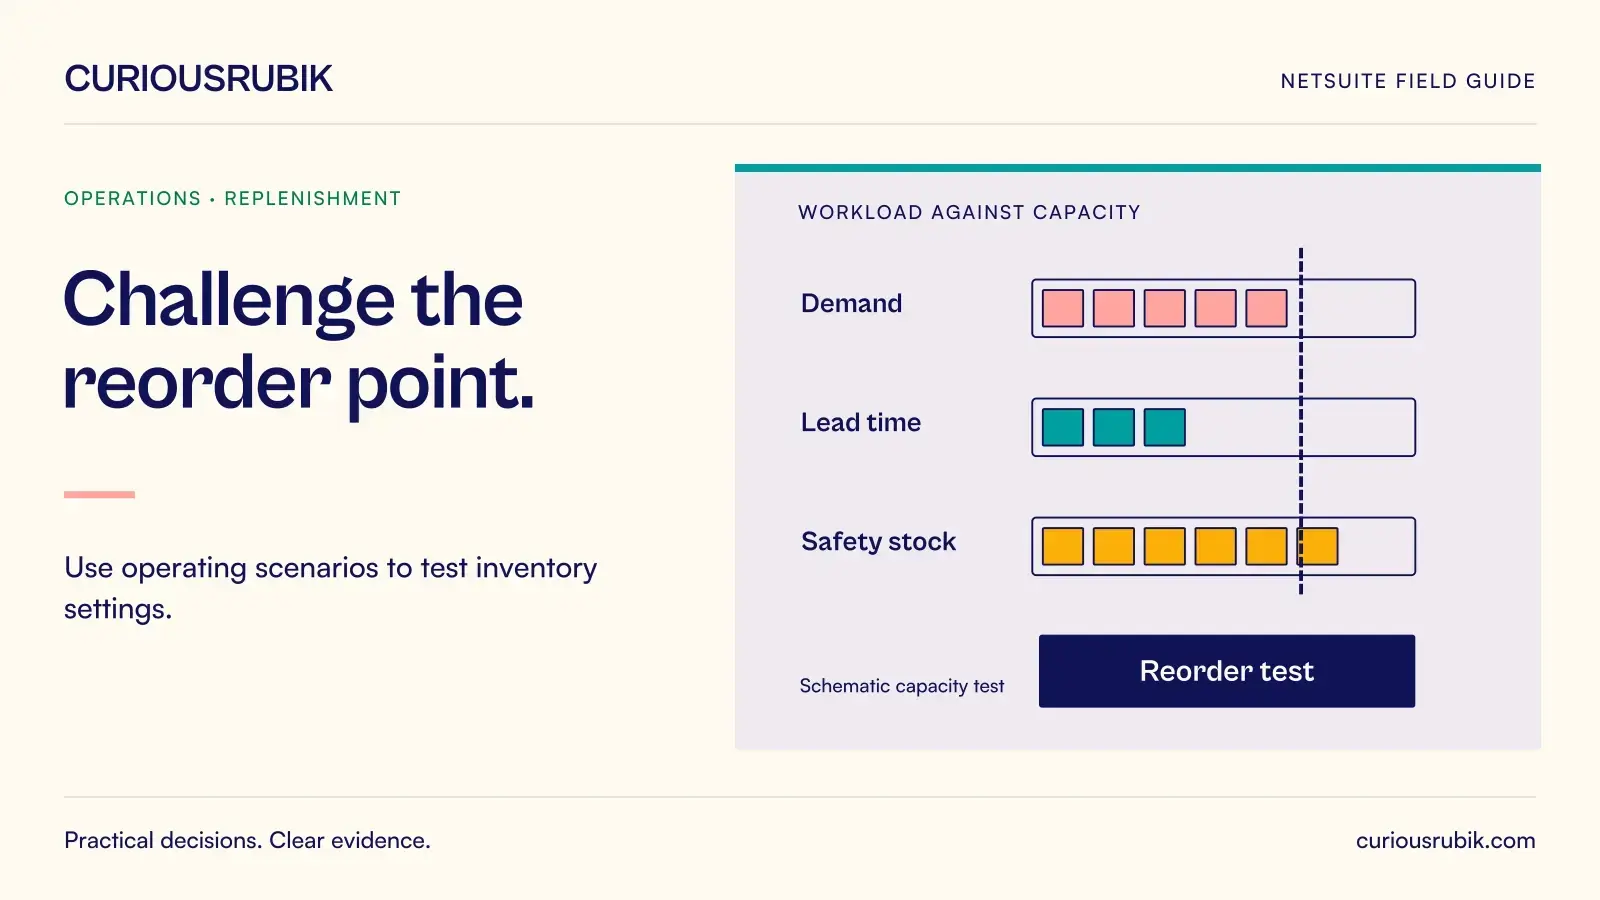
Increasing safety stock can reduce shortages, but it can also conceal an unreliable lead time or an incorrect demand history. Reducing it can release cash while making replenishment more fragile. The useful decision is how much uncertainty …
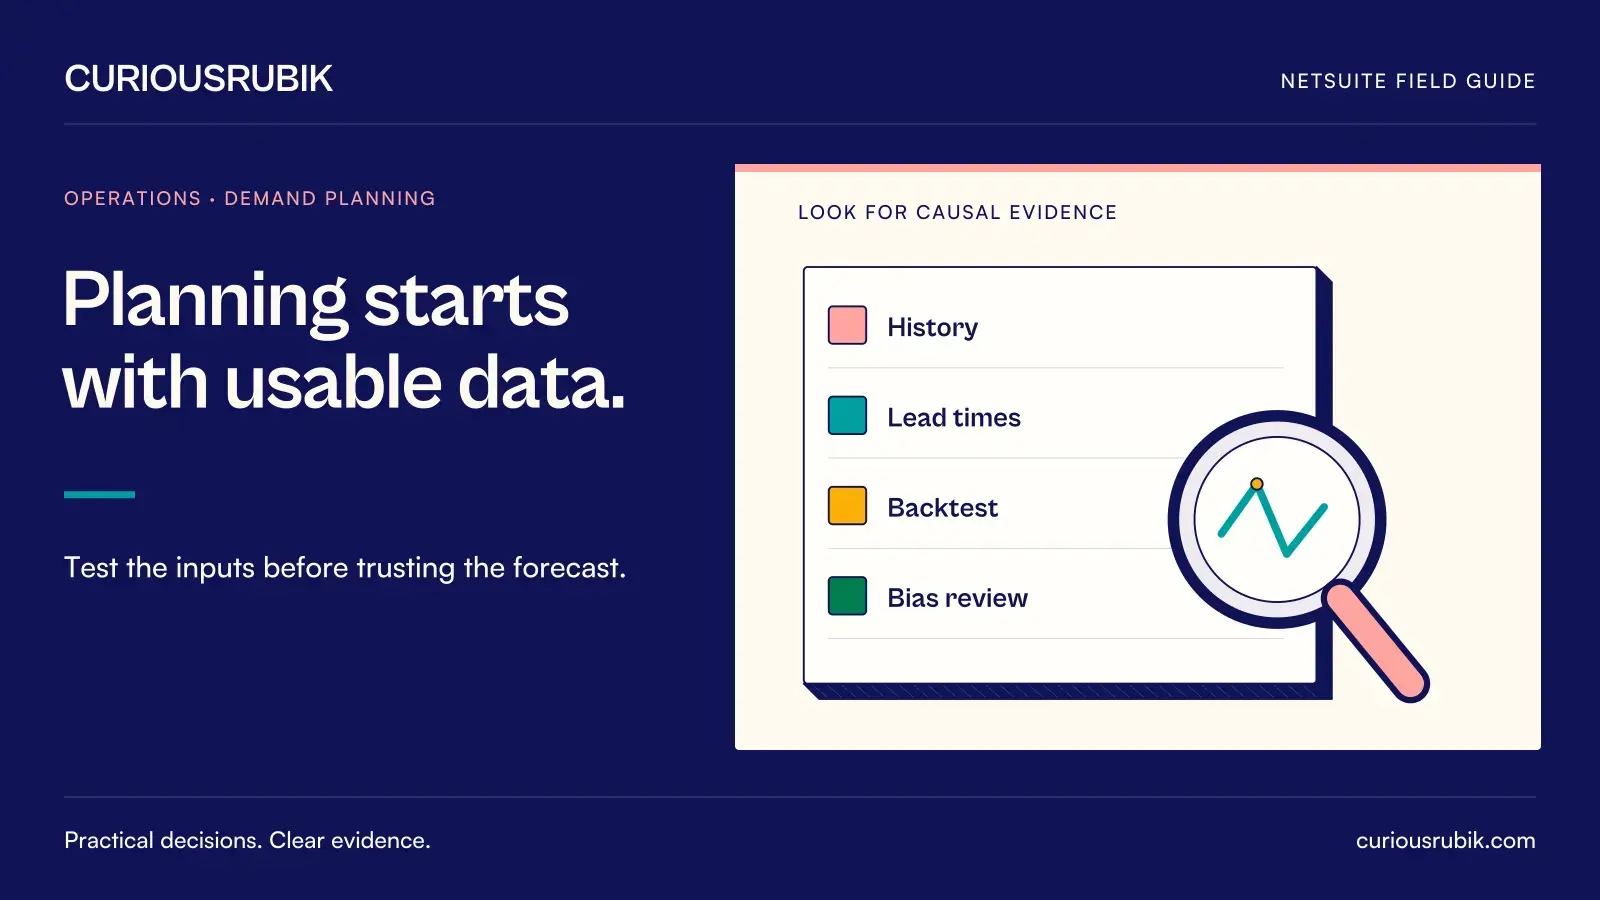
A forecast can be calculated from poor history as easily as from reliable history. The resulting supply recommendations may look precise while repeating stockouts, promotions, and incomplete lead-time assumptions. Demand planning readiness …
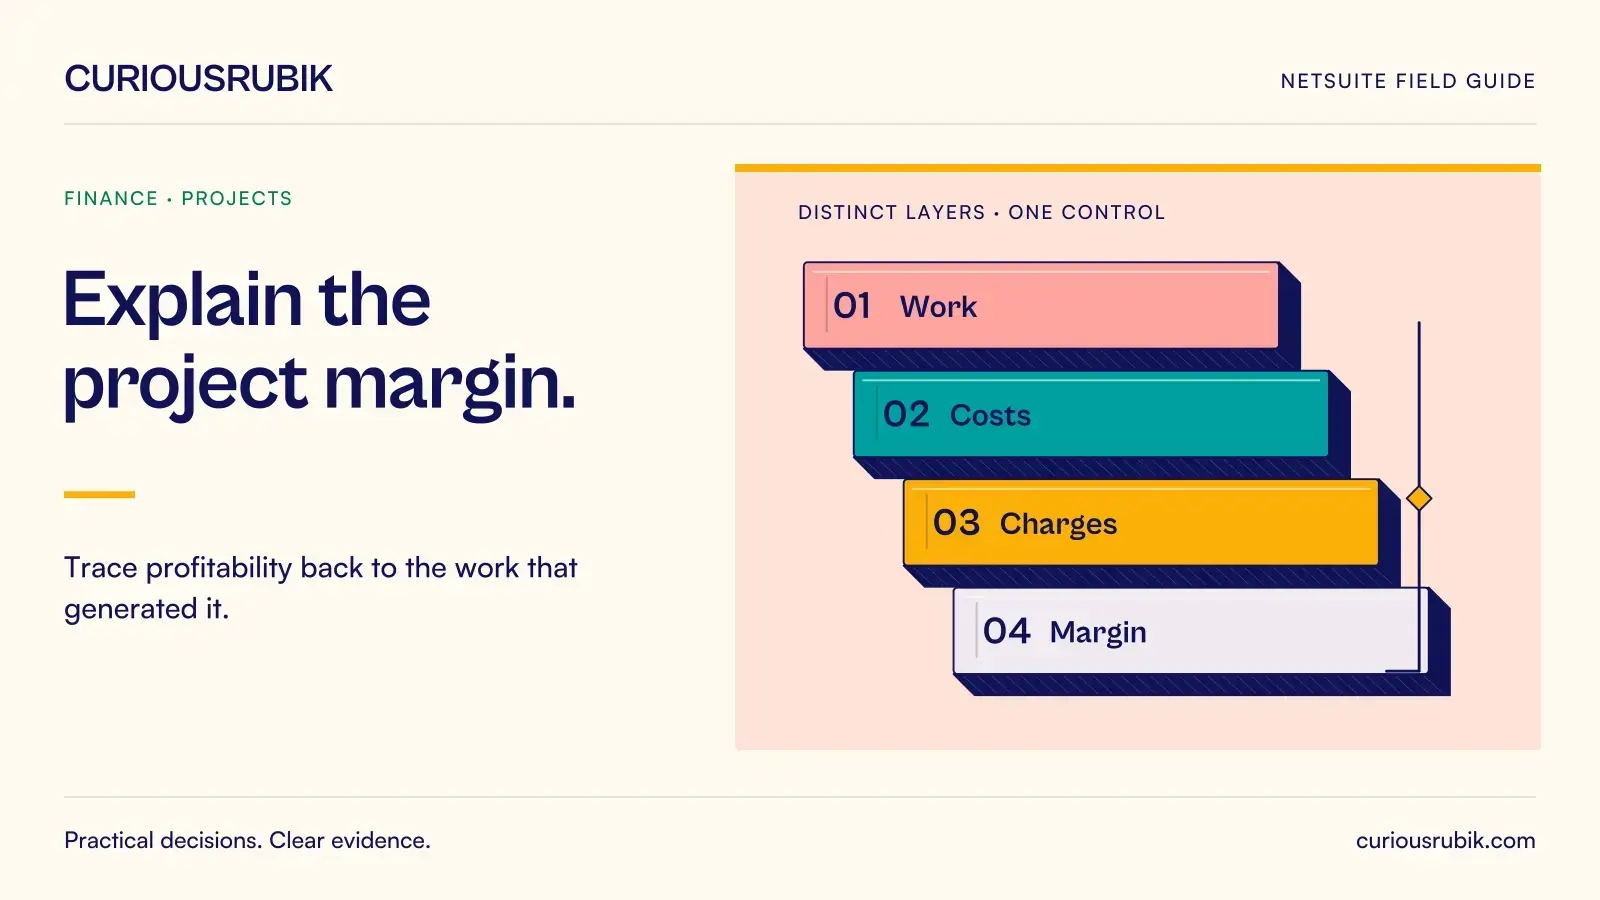
A project can show strong billings and weak recognised margin in the same month. Another can look unprofitable because approved time has not yet reached the cost view. These are different situations, and a single percentage rarely explains …
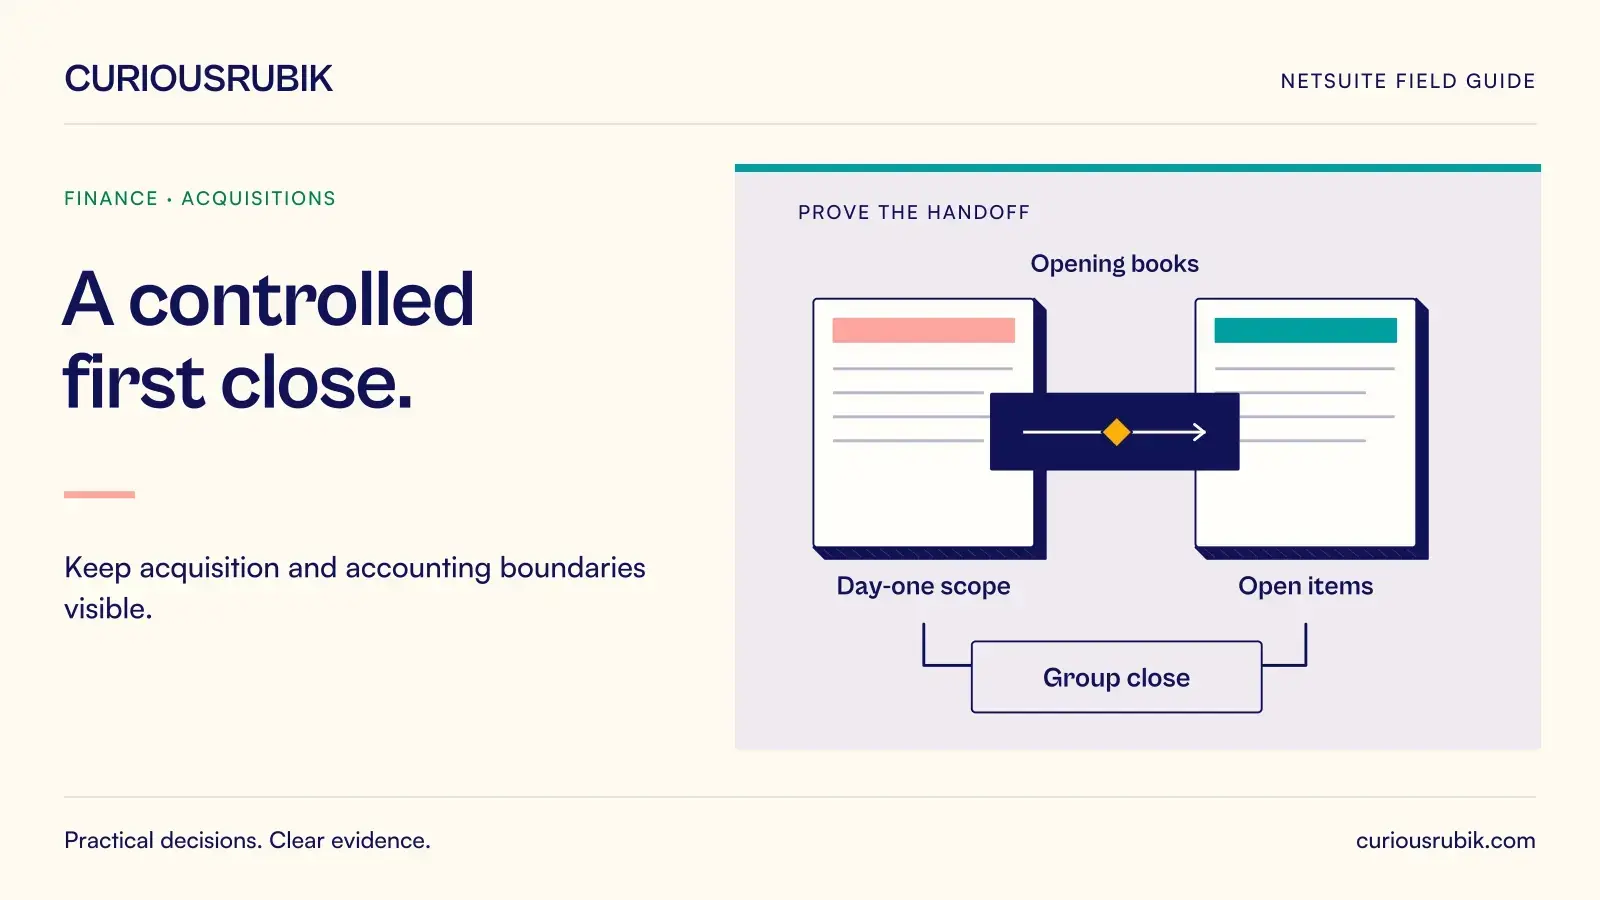
The first close after an acquisition brings together several clocks. The legal transaction has an effective date. The acquired business has its own operational cutoff. Data moves on a migration schedule. Group finance needs a consolidation …
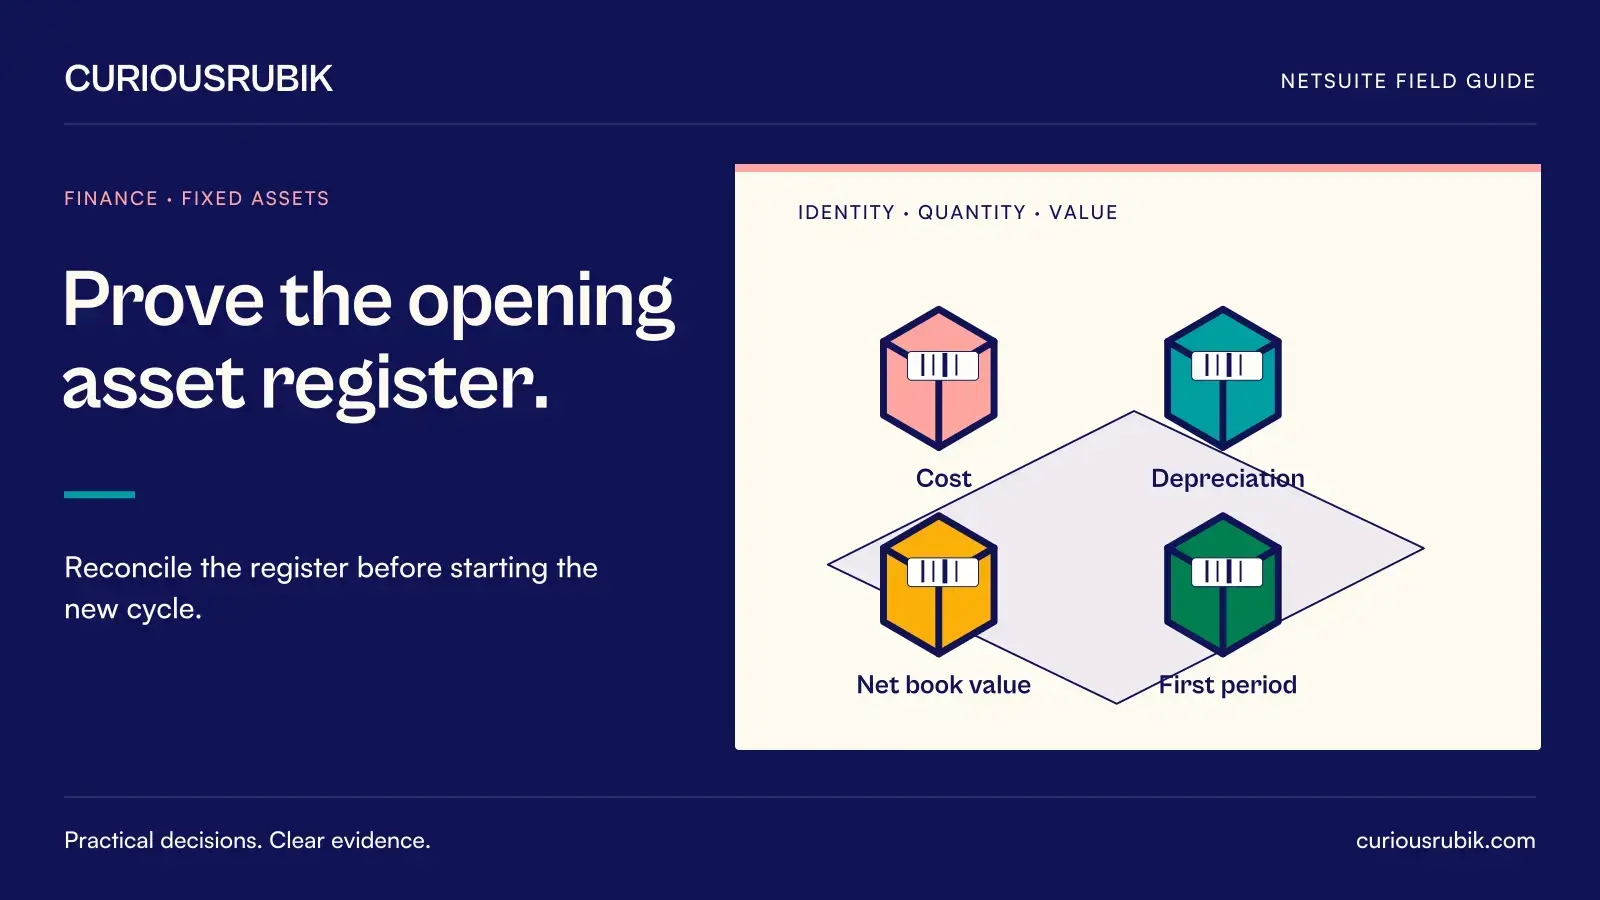
A fixed-assets implementation becomes dependable when the opening register explains the ledger and produces the expected next depreciation charge. Importing asset records is only one part of that result. Missing acquisition dates, …
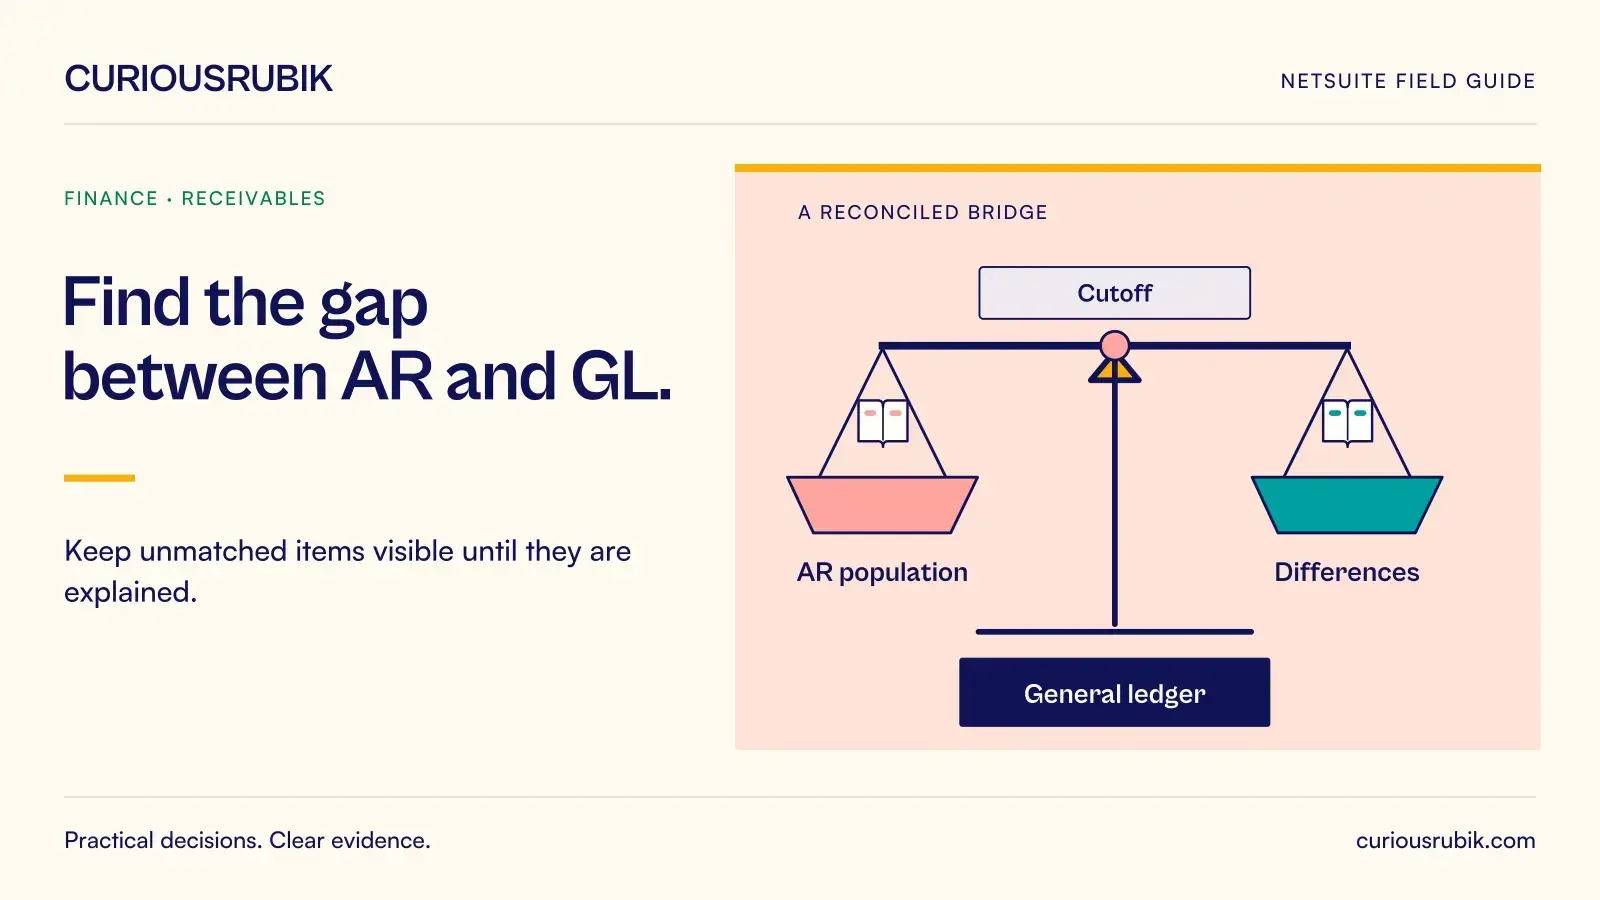
A difference between an accounts receivable aging report and the general ledger deserves an explanation before it deserves a journal. The reports may describe different populations, use different dates, or express balances in different …
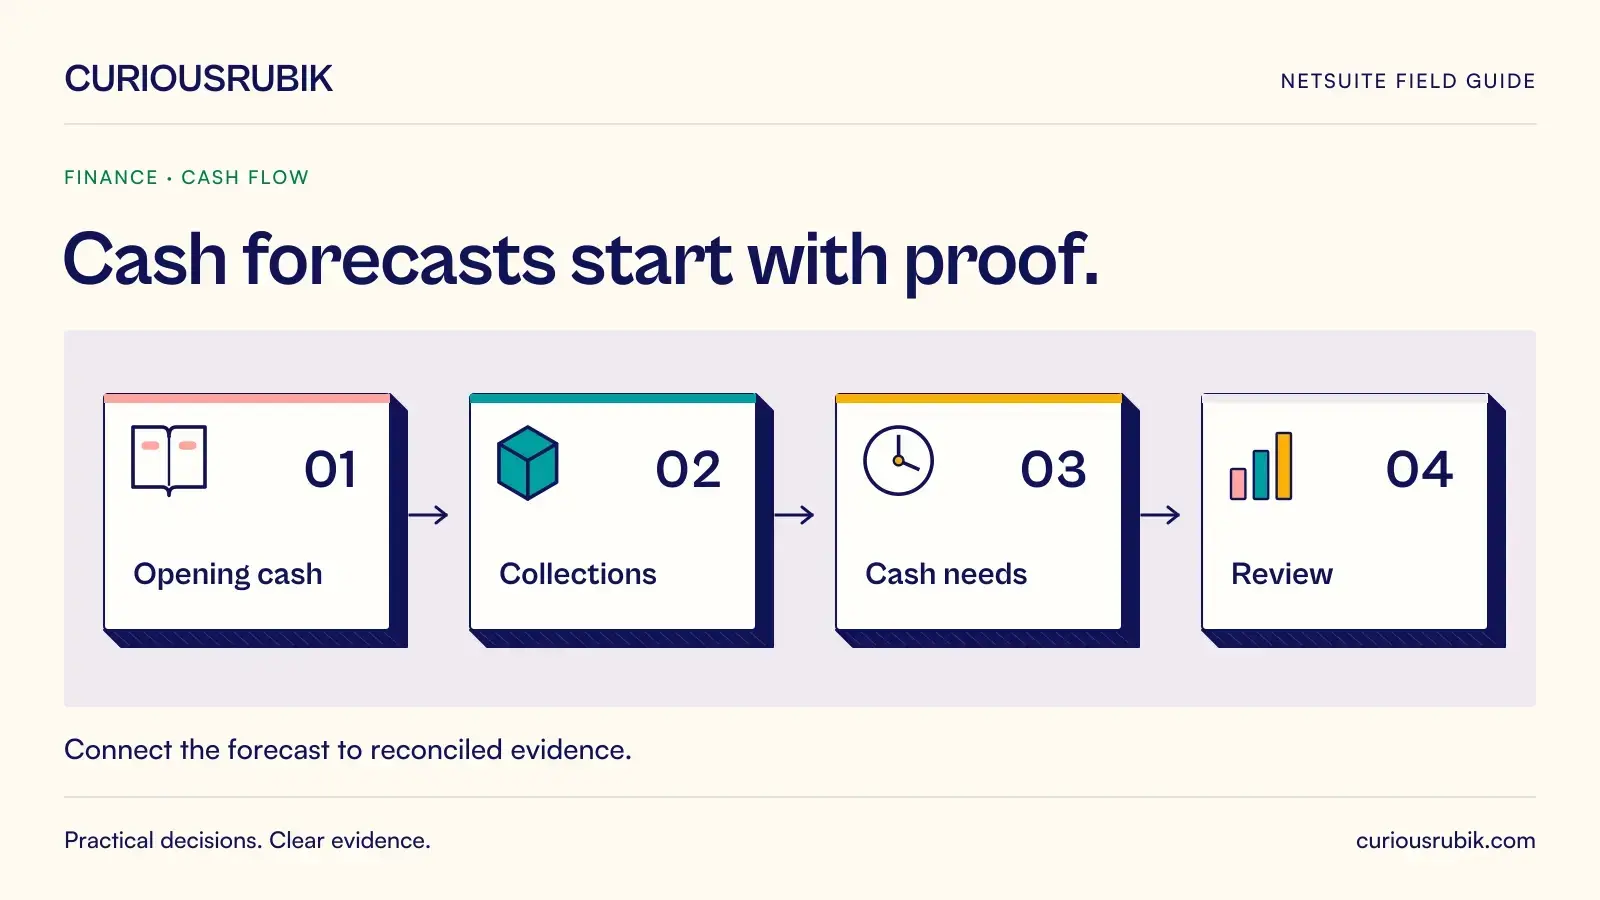
A cash-flow statement and a cash forecast answer different questions. The statement explains historical cash movement. The forecast estimates future receipts and payments using assumptions about timing and activity. Treating them as …
A request for a second set of financial statements does not automatically require a second accounting book. The difference may be a report layout, an account presentation or a genuine change in recognition, measurement or timing. Those …
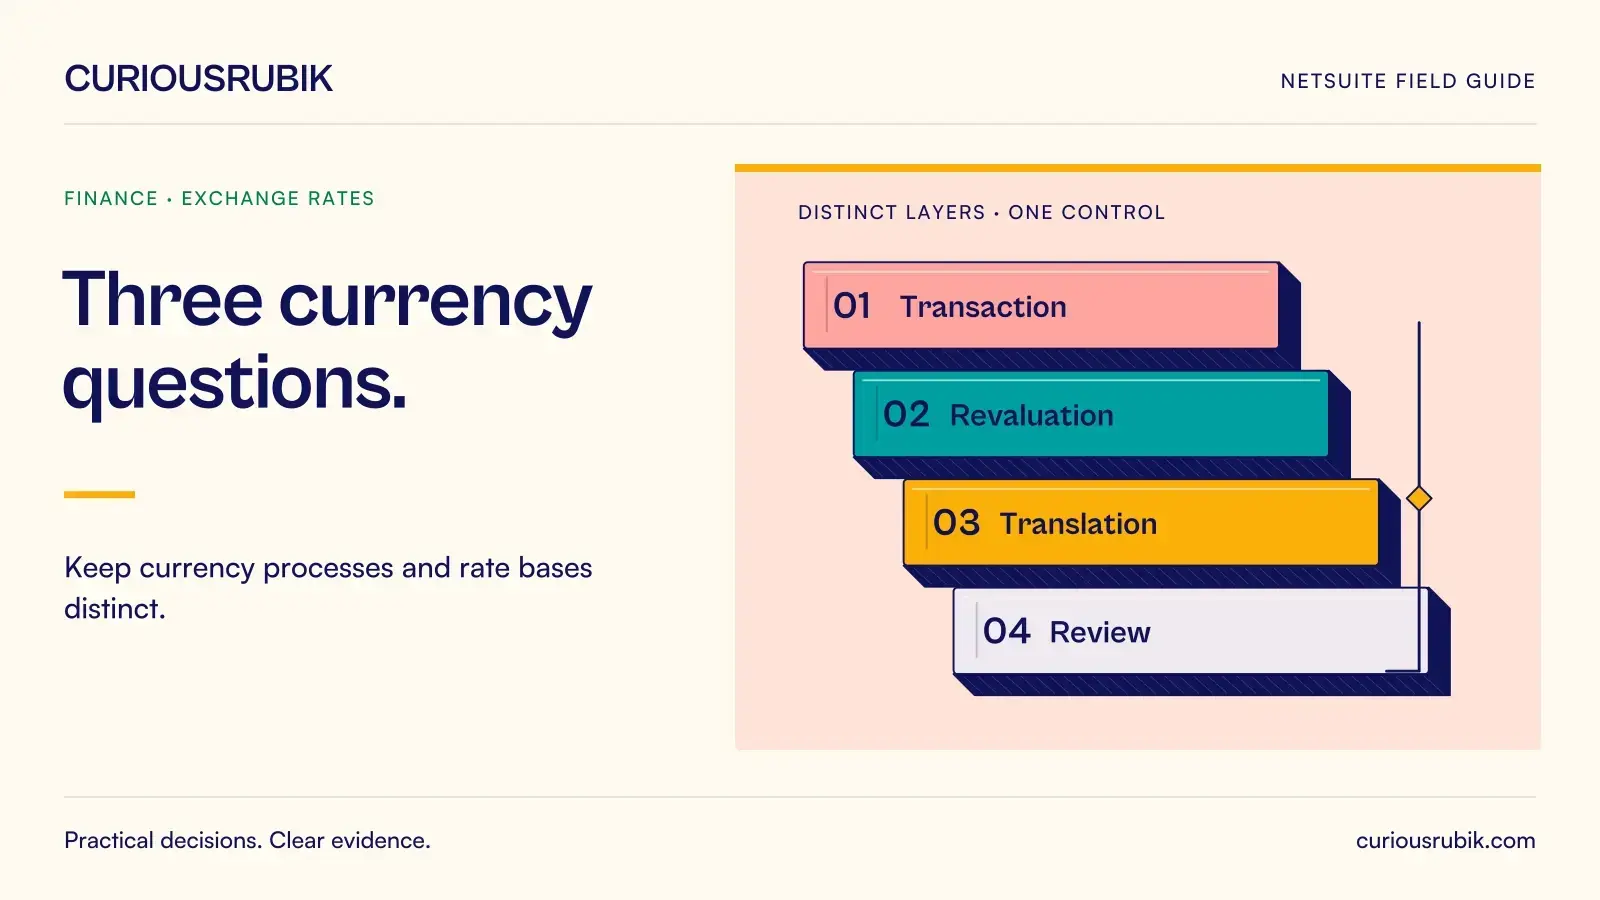
A translation difference can be a normal consequence of applying different rate bases to different accounts. It can also reveal an incorrect period, account classification or subsidiary relationship. Adjusting it before identifying the …
A warehouse management demonstration can look convincing when every label scans, every bin contains the expected quantity, and the order ships in full. Daily operations are less orderly. Receipts arrive short, stock appears in the wrong …
Increasing safety stock can reduce shortages, but it can also conceal an unreliable lead time or an incorrect demand history. Reducing it can release cash while making replenishment more fragile. The useful decision is how much uncertainty …
A forecast can be calculated from poor history as easily as from reliable history. The resulting supply recommendations may look precise while repeating stockouts, promotions, and incomplete lead-time assumptions. Demand planning readiness …
A project can show strong billings and weak recognised margin in the same month. Another can look unprofitable because approved time has not yet reached the cost view. These are different situations, and a single percentage rarely explains …
The first close after an acquisition brings together several clocks. The legal transaction has an effective date. The acquired business has its own operational cutoff. Data moves on a migration schedule. Group finance needs a consolidation …
A fixed-assets implementation becomes dependable when the opening register explains the ledger and produces the expected next depreciation charge. Importing asset records is only one part of that result. Missing acquisition dates, …
A difference between an accounts receivable aging report and the general ledger deserves an explanation before it deserves a journal. The reports may describe different populations, use different dates, or express balances in different …
A cash-flow statement and a cash forecast answer different questions. The statement explains historical cash movement. The forecast estimates future receipts and payments using assumptions about timing and activity. Treating them as …
A request for a second set of financial statements does not automatically require a second accounting book. The difference may be a report layout, an account presentation or a genuine change in recognition, measurement or timing. Those …
A translation difference can be a normal consequence of applying different rate bases to different accounts. It can also reveal an incorrect period, account classification or subsidiary relationship. Adjusting it before identifying the …